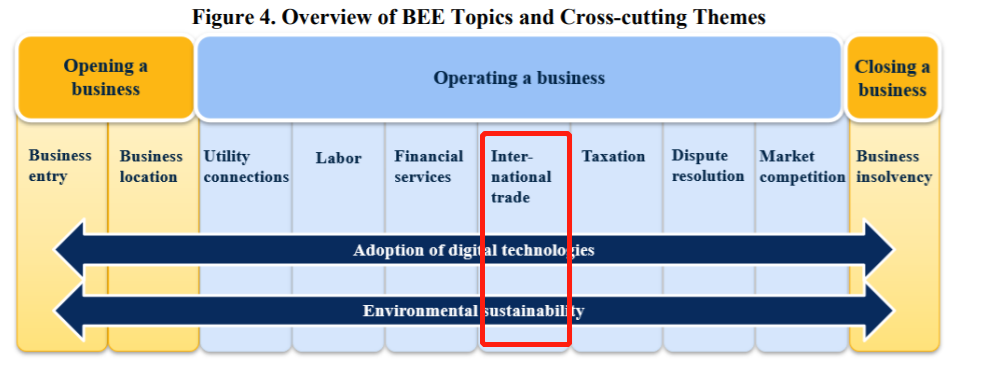
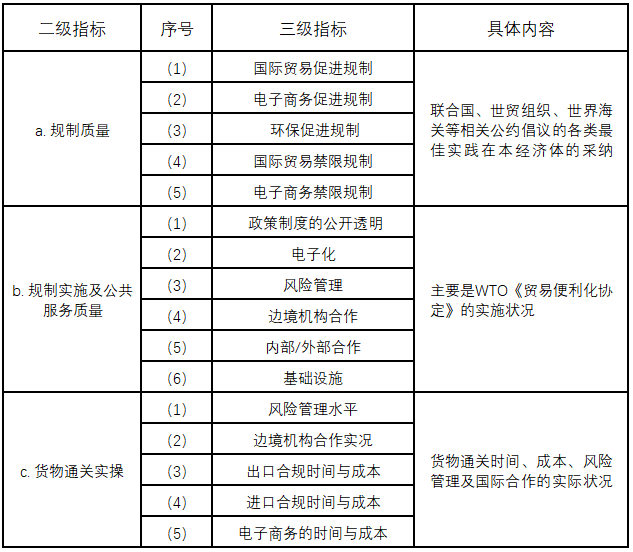
附件内容预览
Pre-Concept Note Business Enabling Environment (BEE) February 4, 2022 Section I. Objective and Principles of the Business Enabling Environment (BEE) Project On September 16, 2021, the World Bank Group (WBG) Senior Management decided to discontinue the Doing Business (DB) report and data and also announced that the WBG would work on a new approach for assessing the business and investment climate. The new approach would improve on its predecessor and be informed by advice from experts in the WBG, as well as the recommendations from qualified academics and practitioners outside the institution, including the External Panel Review on DB methodology. Its design will also take into consideration the views of potential users in government, the private sector, and civil society through an open consultative process. The new benchmarking exercise will be developed in the Development Economics (DEC) Global Indicators Group (where DB used to be housed). This Group will design, pilot, and implement the new benchmarking exercise, under the guidance of the WBG Chief Economist and DEC Senior Vice President. The data collection and reporting process will be governed by the highest possible standards, including sound data gathering processes, robust data safeguards, clear approval protocols, transparency and public availability of granular data, and replicability of results. The objectives and principles of the new project for benchmarking the business environment around the world are as follows: A. Working Title. The working title of the new project is Business Enabling Environment, with the acronym BEE. The title will be refined after due consideration for branding impact. B. Intended Output. The objective of this benchmarking exercise is to provide a quantitative assessment of the business environment for private sector development. This quantitative assessment will produce granular data and a report based on these data, published with regular annual frequency and covering most economies worldwide. Private sector development is here defined by three characteristics: it promotes economic growth through innovation and entrepreneurship;1 it increases equality of opportunities among market participants;2 and it ensures the general sustainability of the economy in the long term.3 Private sector development is driven by the efforts and ingenuity of private entrepreneurs but is critically affected by a range of public policies and regulations that create a conducive business environment. This incentivizes the start-up of new firms, 1 World Bank. 2004. World Development Report 2005: A Better Investment Climate for Everyone. Washington, DC: World Bank. Commission on Growth and Development. 2008. The Growth Report: Strategies for Sustained Growth and Inclusive Development. Washington, DC: World Bank. La Porta, R., and Shleifer, A. 2008. “The Unofficial Economy and Economic Development.” Brookings Papers on Economic Activity 47 (1): 123-135. Dabla-Norris, E., Ho, G., Kochhar, K., Kyobe, A., and Tchaidze, R. 2014. “Anchoring Growth: The Importance of Productivity- Enhancing Reforms in Emerging Market and Developing Economies.” Journal of International Commerce, Economics and Policy (JICEP), World Scientific Publishing Co. Pte. Ltd., vol. 5(02), pages 1-29. 2 World Bank. 2005. World Development Report 2006: Equity and Development. Washington, DC: World Bank. 3 World Bank. 2003. World Development Report 2003: Sustainable Development in a Dynamic World-Transforming Institutions, Growth, and Quality of Life. Washington, DC: World Bank. Commission on Growth and Development. 2008. Ibid. United Nations Conference on Trade and Development. 2020. Entrepreneurship for Sustainable Development: Report of the Secretary-General. Pursuant to General Assembly resolution 73/225. New York: United Nations. 1 the facilitation of existing businesses, the creation of good jobs, and the transition of informal to formal firms.4 C. Development Purpose. BEE’s granular data and summary report will aim to achieve a twofold purpose: (1) to advocate for policy reform and (2) to inform economic research and specific policy advice (Figure 1). Figure 1. BEE Twofold Purpose towards Private Sector Development Therefore, BEE will first aim to promote economic reforms, opening the door for knowledge sharing and policy dialogue for governments, civil society (including the private sector), the WBG, and other development institutions. Second, BEE will provide granular data that can be used for social and economic research and for specific policy advice where detailed information is required. Through its focus on private sector development, BEE should effectively contribute to meet the WBG twin goals of eliminating poverty and boosting shared prosperity.5 Ultimately, the BEE data and reports aim to be a global public good that is useful to institutions and individuals interested in social and economic development around the world. D. Scope. The business environment can be defined as the set of conditions outside a firm’s control that have a significant influence on how businesses behave throughout their life cycle.6 This set of conditions can be very large, from macroeconomic stability to microeconomic regulations. To differentiate the BEE benchmarking exercise from other well-established international measures, the proposal is to concentrate on the regulatory framework and public service provision at the microeconomic level (Figure 2). Microeconomic regulations and services refer to those that are enacted and/or implemented to directly affect firms´ behavior and performance, as well as those of their markets and workers.7 4 De Soto, H. 1989. The Other Path. Harper and Row Publishers Inc., New York. Loayza, N., and Servén, L. 2010. Business Regulation and Economic Performance. Washington, DC: World Bank. Bruhn, M., and McKenzie, D. 2014. “Entry Regulation and the Formalization of Microenterprises in Developing Countries.” The World Bank Research Observer, 29(2), 186-201. 5 Independent Evaluation Group. 2016. Private Sector Development: Recent Lessons from Independent Evaluation. Washington, DC: World Bank. 6 World Bank. 2004. Ibid. Aterido, R., Hallward-Driemeier, M., and Pagés, C. 2011. “Big Constraints to Small Firms’ Growth? Business Environment and Employment Growth across Firms.” Economic Development and Cultural Change, 59(3), 609–647. United Nations Industrial Development Organization. 2017. Improving the Business Environment. Vienna: United Nations. 7 Loayza, N., Oviedo, A. M., and Servén, L. 2010. “Regulation and Microeconomic Dynamics.” In Business Regulation and Economic Performance, edited by Loayza, N. and Servén, L. Washington, DC: World Bank. 2 BEE will, therefore, not cover macroeconomic conditions (for this purpose, see, for instance, Global Economic Prospects), government corruption and accountability (see, for instance, Worldwide Governance Indicators), gender (see, for instance, Women, Business and the Law), human capital (see, for instance, the Human Capital Index), or conflict, crime, and violence (see, for instance, United Nations Office on Drugs and Crime Statistics), to name a few. In order to recognize the relevance of these other issues, the BEE website will feature a section on “complementary resources,” with a presentation of the areas not covered by BEE and links to their most relevant data sources. This will make the BEE website a “one-stop shop,” where people and institutions interested in the business and investment climate can readily obtain information from. This will also serve to clarify the informational gap that BEE is intended to fill, thus highlighting its value-added in the broader context of data and analysis on business and investment climate. Figure 2. BEE Measures the Regulatory Framework and Public Service Provision, together with the Efficiency with which these Two Pillars Are Combined in Practice E. Approach. BEE´s approach may be best understood in contrast to DB.8 It is an attempt to strike better balances as a business environment assessment, as recommended by the External Panel Review (Figure 3). First, BEE will evaluate the business environment not only from the perspective of an individual firm’s ease of doing business but also from the standpoint of private sector development as a whole. Recognizing that there is a tension between the cost to individual firms and the benefits to the whole economy, BEE will include different indicators that address these different perspectives. Second, BEE will not only look at the regulatory burden but also at the provision of public services key for functioning markets. This new balance attempts to provide a more nuanced and potentially positive perspective on the role of governments in creating a conducive business environment. Third, BEE will not only collect de jure information (i.e., according to statutory laws and regulations) but also de facto measurements (i.e., reflecting practical implementation). DB also tried to obtain de jure and de facto data; however, BEE will improve by collecting 8 Appendix I provides a comparison of DB and BEE key features. 3 information directly derived from firm-level surveys. Fourth, and related to the previous point, BEE will try to achieve a balance between data comparability across countries and data representativeness in a given economy. This balance can be achieved by collecting data through a combination of expert consultations and firm surveys, as well as by setting common parameters to guide the data collection (i.e., firm size, sector, type, and ownership for comparability of expert consultations; and representative sampling for firm- level surveys). Figure 3. BEE Attempts to Provide a Balanced Approach when Assessing the Business Environment F. Data Integrity and Transparency. The data collection and reporting process will be governed by the highest possible standards, including sound data gathering processes, robust data safeguards, clear approval protocols, transparency and public availability of granular data, and replicability of results. The Global Indicators Group will engage with the WBG’s Group Internal Audit (GIA) unit to examine the end-to-end process of data collection and reporting, will update and expand the GIA recommendations provided in the context of DB, and will produce a Manual and Guide (where protocols and processes are established clearly in writing). G. Thematic Areas or Topics. The specific topics of analysis covered by BEE are currently under development. They are organized following the life cycle of the firm and its participation in the market: opening, operating, and closing a business. The main topics under consideration include business entry, business location, utility connections, labor, financial services, international trade, taxation, dispute resolution, market competition and business insolvency (Figure 4). These topics are further developed in Section II. The selection of topics is guided by the twofold purpose of the BEE project of (1) advocating for policy reform and (2) informing economic research and specific policy advice. The selection will meet the following criteria: i. Relevance. Based on extensive economic research (elaborated in Section II), each selected topic should have been shown to contribute to the development of the private sector, as defined earlier. 4 ii. Value-added. Each topic should fill an existing data gap. BEE should add value by producing a unique primary dataset with worldwide coverage and comparability. Value may be added, for instance, by studying new areas of an existing topic or by looking at them from an innovative perspective. iii. Complementarity. Only comprehensive microeconomic reforms can have substantial effects on productivity and growth.9 Therefore, BEE will look at a range of topics that complement each other, using the life cycle of a firm as the common thread. Only after these relevant factors are evaluated for all economies, the country-specific binding constraints can be identified and addressed. Figure 4. Overview of BEE Topics and Cross-cutting Themes H. Cross-cutting Themes. Together with the preliminary topics listed above, BEE will look at two cross- cutting themes relevant across topics. They are the adoption of digital technologies and environmental sustainability. On digitalization, for instance, most topics will include the assessment of electronic single windows and online one-stop shops. Likewise, on environmental sustainability, for instance, some topics will include the assessment of environmental licenses and the presence of green tax incentives. I. Indicators. Within each topic, BEE will analyze a number of specific indicators based on the following components and criteria: i. Components. For each topic, indicators will be divided in three groups, the first two representing the regulatory and public service pillars, and the third measuring the efficacy with which the two pillars are combined in practice. - Regulatory framework: will consider the quality of regulations, using, to the extent possible, the best practices of transparency, clarity, predictability, and relevance, as well as internationally recognized topic-specific best practices. - Public services: will consider the institutional setup, infrastructure, and programs that allow governments to provide directly or through private firms the public services critical for functioning markets. - Overall efficiency: will measure the efficiency with which the goals of each topic are obtained in practice as experienced by the private sector. It will be assessed through firm-level surveys and/or expert consultations. 9 Bergoeing, R. Loayza, N., and Piguillem F. 2016. The Whole Is Greater than the Sum of Its Parts: Complementary Reforms to Address Microeconomic Distortions. Washington, DC: World Bank. 5 ii. Criteria. The selection of indicators will be guided by the following criteria: - Balanced approach between de jure and de facto indicators within each topic. De jure indicators will analyze the business environment based on statutory regulations, laws, and jurisprudence, whereas de facto indicators will analyze how regulations and government services are implemented in practice as experienced by the private sector. Each BEE topic will combine de jure and de facto indicators in order to provide a more comprehensive assessment of the business environment. - Balanced approach between indicators focused on individual firms and indicators focused on the private sector as whole. Certain BEE indicators may be more targeted at assessing the business environment from the perspective of an individual firm (e.g., indicators on the efficiency of implementation of utility connections). Other BEE indicators may be more focused on the general private sector. This later group of indicators will account for equality of opportunities across markets participants as well as for the growth and sustainability of the private sector as whole, beyond an individual firm’s interest (e.g., environmental standards for utility connections). - Indicators should be seen as good proxies and not expected to be exhaustive. Indicators should be seen as a set of reasonable proxies that span the most relevant areas of the business environment and the issues that are becoming increasingly important (e.g., the adoption of digital technologies and processes). They are not expected to be fully exhaustive or detailed as this would exceed the team’s resources and likely not be cost-efficient. Moreover, the indicators will be limited to business environment conditions and not cover the final outcomes of such conditions. Firm and market outcomes are the complex result of different variables, including demand and supply forces. As such, they are beyond the scope of BEE. - Indicators should be quantifiable, based on primary data, and actionable. They will focus on areas that can be measured in an objective and comparable manner across countries. Since the aim of BEE is to produce primary data, indicators should be designed in a way that they can be collected through a combination of expert consultations and firm surveys. Indicators should also be actionable; that is, they should be amenable to reform through government policies. To the extent possible, indicators should focus on areas where there is an established “good-practice” to facilitate comparisons. Details on the indicators are developed in Section II and summarized in Appendix II. J. Scoring. Quantifying business environment conditions into corresponding measurable indicators is critical for this benchmarking exercise. How these indicators will be grouped to produce aggregate scores, by topic or even by economy, is yet to be decided. Either way, the hype around aggregate rankings will be avoided. Aligned with the recommendations provided by the External Panel Review and the WBG Independent Evaluation Group,10 BEE will explore different ways of presenting summary information for maximizing public interest and motivating reforms (e.g., distance-to-frontier scoring, grouping by quintiles, and scoring per topic). K. Trade-offs. The BEE project acknowledges that the current approach faces some trade-offs in relation to its broader focus on the private sector, limited scope of the business environment, use of proxy measures, and treatment of incumbent vs. potential entrant firms. These are detailed in Table 1. 10 Independent Evaluation Group. 2013. Independent Panel Review of the Doing Business Report. Washington, DC: World Bank. 6 Table 1: Trade-offs Faced by the BEE Project Advantages Limitations Solutions Focus on BEE assesses business BEE will not BEE acknowledges that some private regulations affecting necessarily assess business regulations (e.g., certain sector private sector business regulations regulations related to taxation) development development as a only affecting may add to the regulatory burden whole. individual enterprises. faced by individual firms but recognizes the positive impact that they may have on the economy. BEE will attempt to address this trade-off when deciding on the scoring methodology. Limited BEE focuses on BEE does not include The BEE website will feature a scope in the producing unique all aspects that could section on complementary topics primary data in a affect private sector resources, with well-established assessed for limited number of development; for international measures (e.g., the business areas relevant for instance, corruption from Worldwide environment private sector macroeconomic Governance Indicators), which development where conditions, interested people and institutions BEE adds value. corruption, or gender can consider and access. equality are not included. Indicators Indicators focus on the Indicators are not BEE will clarify the scope and are proxies regulatory framework exhaustive and certain rationale of each indicator on the and the provision of details and areas for BEE website, as well as during public services the firm and the interactions with stakeholders. If relevant for the topic market will not be necessary, it will replace its and should be seen as covered. indicators by others that are proven to be better proxies. proxies that span most relevant areas for the business environment. Limited use Makes data more May potentially limit Use a combination of expert of representative across the level of details consultation and firm-level surveys standardized firms and sectors that can be collected as needed. Besides, BEE will add a case within the economy. and compared across set of parameters to ensure scenarios economies. comparability of data as needed (e.g., type of utility connection). Entrants vs. For topics related to May potentially For topics where entry and exit incumbent operating a business, underestimate entry barriers could be potentially firms BEE collects data and exit barriers by underestimated by incumbent through a combination focusing on firms that companies (i.e., business entry, of expert consultations are currently business insolvency), BEE will and firm surveys operating in the mainly collect data through expert among incumbent market. consultations. companies. 7 *** The rest of the pre-concept note is organized as follows. Section II presents BEE’s topics, their motivation and grounding in the literature, and their corresponding indicators. The topics are organized following the life cycle of the firm: opening, operating, and closing a business. For each topic, the indicators are grouped into three categories: regulations, public services, and efficiency of implementation. And for each indicator, the type of measure (de jure or de facto) and the mode of data collection are indicated. Section III briefly introduces some features of implementation of the project, namely, the data collection approach and the required skill set. It also includes a proposed timetable for the project. The pre-concept note represents work-in-progress. It is intended to elicit feedback and inputs from experts around the WBG and other development institutions, as well as civil society and private sector organizations, academics and practitioners. These inputs will be incorporated in a Concept Note to be circulated in a formal Bank-Wide Review in late-March and discussed in the Bank-Wide Review Meeting in April 2022, chaired by WBG Chief Economist and DEC Senior Vice President. 8 Section II. Topics, Motivation, and Corresponding Indicators A. Business entry 1. Motivation Aspiring entrepreneurs often encounter barriers to entry into the formal economy. Where the rules are burdensome, resource-constrained entrepreneurs might not have the opportunity to turn their ideas into a business that benefits from a level playing field. Registered companies can receive a multitude of advantages including the legal and financial services provided by courts and banks. Their employees enjoy social security protection. The economy itself benefits from positive spillovers: where formal entrepreneurship is high, job creation and economic growth also tend to be high.11 Moreover, as more businesses formalize, the tax base can expand, enabling the government to spend on productivity-enhancing areas and pursue other social and economic policy objectives. There is strong evidence that higher costs for business start-ups are associated with lower business entry and with lower levels of employment and productivity.12 Cumbersome regulations for business start-ups are associated with high levels of corruption and informality. 13 A simple business start-up process is a critical factor for fostering formal entrepreneurship. 14 Digital technology and transparency of information can encourage businesses to register and promote private sector growth. Digital public services can address the concerns of entrepreneurs by reducing the compliance cost of interacting with government authorities. Electronic business registration and electronic payments are among e-government initiatives used to encourage business formalization. 15 In addition, transparent and accurate data on registered businesses are an important building block of a good business environment, because they give governments the tools to produce business statistics and design relevant policies, and they give market participants the information they need to assess their risks in investing or entering a market. 2. Indicators in the area of business entry BEE uses three sets of indicators in the area of business entry: (a) the quality of regulations for business entry (regulatory framework pillar), (b) the digital services and transparency of information for business start-ups (public services pillar), and (c) the efficiency of the process to open a business (a measurement that reflects the impact of the two previous pillars). Compared to the previous Starting a Business topic of Doing Business, the BEE indicators will cover new issues and will have a broader scope. The quality of regulations for business entry is the first new area – measuring the good practices for business start-ups and the restrictions for business entry. The BEE indicators will incorporate international aspects of business entry and will cover both domestic and foreign private firms. The availability of digital public services and transparency of information for business start- 11 Fritsch, Michael, and Florian Noseleit. 2013. “Investigating the Anatomy of the Employment Effect of New Business Formation.” Cambridge Journal of Economics 37 (2): 349–77. 12 IEG Issues Paper, Doing Business and Country Reforms. June 22, 2021. Page 45. Among the papers used: Bruhn, Miriam. 2012. “A Tale of Two Species: Revisiting the Effect of Registration Reform on Informal Business Owners in Mexico.” Journal of Development Economics 103-1. 13 Klapper, Leora, and Inessa Love. 2011. “The Impact of Business Environment Reforms on New Firm Registration.” Policy Research Working Paper 5493, World Bank, Washington, DC. 14 Klapper, Leora, Anat Lewin and Juan Manuel Quesada Delgado. 2009. "The Impact of the Business Environment on the Business Creation Process." Policy Research Working Paper 4937, World Bank, Washington, DC. 15 International Labour Organization. 2021. Small goes digital How digitalization can bring about productive growth for micro and small enterprises. 9 ups is the second new area. The efficiency of business entry will build on the previous Starting a Business indicator and will be the measurement that reflects the impact of the two previous pillars. a. Quality of regulations for business entry This set of indicators intends to measure two different aspects of the regulatory framework for business start-ups: (1) good regulatory practices for business incorporation, and (2) restrictions on business entry for domestic and foreign private firms. The definition of domestic and foreign firms will be decided upon consultation with external experts, civil society, governments and interested stakeholders. Data for this de jure indicator can be collected through expert consultations (lawyers, notaries, accountants and tax advisors who are very familiar with the regulatory framework for business entry) and corroborated through desk research. (1) Good practices in the regulatory framework for business incorporation – This indicator serves as a proxy for assessing whether the applicable regulatory framework includes good practices promoting a safe and secure environment for business start-ups. A good business environment that enables formal entrepreneurship is critical to unleashing the potential of new firms. This indicator builds on the UNCITRAL guidelines and principles for business registries,16 the annual publications of the Corporate Registers Forum (CRF)17, the Financial Action Task Force (FATF) standards18 and previous research on good practices conducted by DECIG.19 Some of these good practices are the safety checks in the legislative framework for company incorporation and operations. For instance, to avoid fraudulent activity or corporate identity theft, it is important to have mandatory verification of the company name or mandatory verification of the identity of the entrepreneurs. The BEE indicators will also assess whether the involvement of third-party professionals is optional (e.g., lawyers, accountants, notaries) for business registration. Allowing entrepreneurs to file registry-provided standard incorporation documents electronically with the business registry can facilitate automatic information validation and reduce costs.20 Another critical area to ensure adequate transparency and help prevent the misuse of companies for money laundering or other illegal activities is related to the registration of information on beneficial owners when entrepreneurs start a new business – submitting the necessary information and including verifications inherent to beneficial owners. When changes arise (e.g., changes in company name, shareholders information, beneficial ownership information), it is also imperative that the regulatory framework defines rules and deadlines to make necessary updates in the business registry. (2) Restrictions in the regulatory framework for business entry – This indicator assesses regulatory restrictions for business entry for both domestic and foreign private firms. Entry restrictions hinder the potential of establishing new firms. This indicator builds on the OECD research on FDI restrictions and market entry21, the annual publications of the Corporate Registers Forum22 and research by DECIG and the Investing Across Borders report.23 16 UNCITRAL Legislative Guide on Key Principles of a Business Registry, https://uncitral.un.org/sites/uncitral.un.org/files/media-documents/uncitral/en/lg_business_registry-e.pdf 17 The International Business Registers Report, https://www.corporateregistersforum.org/news/international-business-registers- report/ 18 FATF (2012-2021), International Standards on Combating Money Laundering and the Financing of Terrorism & Proliferation, FATF, Paris, France, www.fatf-gafi.org/recommendations.html 19 DECIG (World Bank) conducted research on good practices in the area of business registration in the past 4 years. 20 Coste, Cyriane, Marie Delion, Adrián González, Frédéric Meunier, Nathalie Reyes, and Yuri Valentinovich. 2019. “The Involvement of Third-Party Professionals in Business Registration and Property Transfer.” World Bank Research and Development Center in Chile, Indicators Group Research Note. World Bank, Washington, DC. 21 OECD FDI Regulatory Restrictiveness Index: https://www.oecd.org/investment/fdiindex.htm; and Product Market Regulations Indicators: https://www.oecd.org/economy/reform/indicators-of-product-market-regulation/. 22 Corporate Registers Forum (CRF) Annual Reports 23 World Bank, Investing across Borders 2010: Indicators of Foreign Direct Investment Regulation in 87 Economies 10 Restrictions for domestic private firms can either be general or specific. Among the general restrictions, all entrepreneurs might have to pay a specific minimum amount of capital for business incorporation, obtain a specific operating license / municipal license / environmental license; or prove that they comply with a minimum level of education or training. Restrictions can apply to activities with specific environmental impact or a specific risk level. Specific restrictions may also apply to domestic entrepreneurs in certain socio-demographic groups, if they face additional requirements when they want to open a bank account or open their own company. Restrictions for domestic private firms can apply to some specific sectors. There are some sector-specific restrictions where private domestic participation or equity ownership is limited (for instance, in the areas of energy, media, telecommunications). Similarly, restrictions for foreign private firms can either be general or specific. In addition to the general restrictions that apply to domestic private companies, foreign private firms face limitations on ownership or dividend distribution, or need to comply with additional requirements (e.g., authentication of documents in foreign languages; general investor licenses). There are also some sector-specific restrictions where foreign participation or ownership is limited (for instance, in the areas of energy, media, telecommunications). b. Digital public services and transparency of information for business start-ups Three indicators of the digital public services and transparency of information for business start-ups have been identified. These are: (1) availability of online services for business incorporation and beginning of operations, (2) interoperability of services for business incorporation and beginning of operations, and (3) online availability of corporate information and transparency of information. Data for this de facto indicator can be collected via expert consultations with all those involved in the process of opening a business and corroborated with administrative data from business registries. The questions would measure the availability of public services in a digital format for entrepreneurs and build on the annual publications of the Corporate Registers Forum and previous research on good practices conducted by DECIG in the past. These indicators serve as proxies for assessing the availability of online public services and information for prospective entrepreneurs. E-government services can enhance the quality of interactions with businesses and citizens, such as facilitating more transparent processes, and reducing time for business registration and minimizes asymmetries of information. (1) Availability of online services for business incorporation and beginning of operations – This indicator assesses the quality of infrastructure at the business registry and any other relevant agency through the availability of online public services for new entrepreneurs. For instance, it would measure if there is an automated and electronic system to verify the uniqueness of company names, an electronic system that covers the entire company registration process, electronic payment for all fees related to company incorporation, electronic signatures, digital ID, and electronic filing for beneficial ownership information, among others. Where applicable, it would also measure if unified registration procedures are in place and environmental licensing requirements are integrated, specifically simplified environment-related notification for activities with low or negligible environmental impact. The coverage and the availability of online services will be considered upon consultation with external stakeholders. (2) Interoperability of services for business incorporation and beginning of operations – This indicator assesses the availability of electronic systems to exchange information across the agencies involved in the process of setting up and operating a business such as the business registry, tax administration, and social security agency. By linking or unifying the databases of the agencies involved in the registration 11 process, the risk of errors and the administrative burden of submitting the same information to multiple agencies for company identification can be reduced. (3) Availability of company information online and transparency of information – This indicator assesses the degree of transparency and accessibility of online information at the business registry. For instance, it would measure if the business registry provides public access to information on the names of companies, the name of directors, the name of shareholders, among others. In addition, it would measure whether the fees, requirements and documentation needed to incorporate and operate a company (including, where applicable, environmental licensing requirements) are easily accessible online on an official website. This increases transparency, reduces information asymmetry, and enhances sound business decisions. c. Efficiency of business entry This set of indicators measures the time and cost to complete the different steps that an entrepreneur must undergo to setup and formally operate a company - such as the company name verification, company registration, tax registration, VAT registration, employer and employee registration, and other steps that are not commonly done in practice in all economies but required in some, such as the need for a general operating license, municipal registration, or a third-party professional involvement. Data for this de facto set of indicators can be best collected through expert consultations, involving professionals who are familiar with the business incorporation process because they help many entrepreneurs go through the process on a regular basis. These experts - lawyers, notaries, accountants, tax advisors - are more informed respondents than individual entrepreneurs who may only go through the business entry process once. During the consultation phase with external stakeholders, the team will consider the possibility of collecting data on the list of agencies that entrepreneurs have to interact with to open a business. To collect data on time and cost, specific parameters on the company’s legal type, size, ownership structure and sector of activity will be necessary to limit the scope of data collection and ensure comparability of data. These indicators serve as proxies for assessing the cost of complying with regulations for business entry. Firms can lack the time and resources to navigate complex regulatory requirements. Reducing the overall cost of compliance can reduce potential barriers for the private sector to operate formally. 12 B. Business location 1. Motivation Location matters. Acquiring the physical space where a business will operate is a crucial ingredient of success for many firms, even in the digital age. Getting the right location can influence business access to customers, transportation, labor, and materials, and determine the taxes, regulations and environmental commitments they must follow.24 Whether an entrepreneur is leasing25 or purchasing a commercial property, the regulatory framework and the public services related to acquiring a location can impact on how conducive the business environment is for individual firms and the private sector development of an economy. Firms are more likely to invest in economies with strong property rights as this will instill more confidence that their investment in immovable property will be safe. 26 Looking at how well the administration of property rights functions gives a good indication of the country’s prospects for economic growth27 and provides confidence to the private sector in investing in strategic locations for business. The quality and transparency of land administration are also vital in helping to eradicate information asymmetry and increase the efficiency of the market. A reliable land administration system provides clear information on property ownership, facilitates the development of real estate markets, and supports the security of tenure. When investors and entrepreneurs acquire a new location for their business, the process often involves licensing requirements for either altering a property or changing tenancy. Building-related permits are essential for public safety, strengthening property rights and contributing to the process of capital formation. Last but not least, clear and easily accessible environmental regulations related to building control avoid posing any redundant compliance burden on firms. 2. Indicators in the area of business location BEE uses three sets of indicators in the area of business location: (a) the quality of regulations for immovable property lease, property ownership and urban planning (regulatory framework pillar), (b) the quality of public services and transparency of information (public services pillar), and (c) the efficiency of key services in getting a business location (a measurement that reflects the impact of the two previous pillars). In contrast to the previous Dealing with Construction Permits and Registering Property topics of Doing Business, the BEE topic will cover new areas and will not be limited to the experience of domestic SMEs. For example, the quality of regulations will include measures of restrictions on property leasing. Furthermore, the indicators will also cover environmental concerns in the areas of green building regulations and environmental clearances. Other important additions, explained in more detail below, will include a larger focus on public services and assessing whether the regulations and government services are provided in a cost-effective and time-efficient manner in practice. a. Quality of regulations for immovable property lease, property ownership and urban planning 24 Carlson, Virginia. 2000. "Studying Firm Locations: Survey Responses vs. Econometric Models." Journal of Regional Analysis and Policy, Mid-Continent Regional Science Association 30 (1):1-22. 25 Adenuga, A.H.; Jack, C. and McCarry, R. 2021. “The Case for Long-Term Land Leasing: A Review of the Empirical Literature”, Land, MDPI 10 (3): 1-21. 26 Johnson, Simon, McMillan, Jhon, and Christopher Woodruff. 2002. “Property Rights and Finance.” The American Economic Review 92 (5): 1335-1356; Soto, Hernando de. 2000. “The Mystery of Capital: Why Capitalism Triumphs in the West and Fails Everywhere Else.” New York: Basic Books. 27 Greena, Alan, and Christine Moserb. 2013. “Do Property Rights Institutions Matter at the Local Level? Evidence from Madagascar.” The Journal of Development Studies 49 (1): 95-109. 13 This set of indicators intends to measure: (1) good regulatory practices for land administration, (2) good regulatory practices for building regulations, and (3) restrictions on leasing and ownership of properties. Data for this de jure set of indicators can be collected through expert consultations with lawyers, notaries, architects, and engineers. Additionally, consultations can be conducted with public officials familiar with the regulatory framework for real estate transactions, the building permitting processes and related environmental clearances, including Environmental Impact Assessments (EIAs). Data collection will be corroborated through desk research. (1) Good regulatory practices for land administration – This indicator assesses whether the regulatory framework includes good practices promoting good governance in the land administration system. It is inspired by the Land Governance Assessment Framework (LGAF), which provides principles and policy recommendations on land governance.28 Some of the good practices will include but not be limited to clear and publicly accessible laws on ownership and leasing, secure land tenure (state or private guarantee), safeguards in place to minimize the risks of land disputes29 and publicly available service standards to avoid delays and corruption.30 (2) Good regulatory practices for building regulations – This indicator assesses whether the building regulatory framework includes good practices promoting safety mechanisms and green building regulations.31 It builds on previous research on good practices conducted by the DEC Global Indicators Group and by the Investment Climate Department of the World Bank Group. Some of the good practices will include but not be limited to whether building regulations are clear and publicly accessible and whether regulations provide for safety mechanisms in construction, such as pre- approvals of building plans by qualified professionals or mandatory inspections. In addition, this indicator will look at environmental licensing requirements as well as regulatory standards specified in green building energy codes.32 (3) Restrictions on property leasing and ownership – This indicator assesses regulatory restrictions on leasing and ownership for domestic and foreign firms. Cumbersome regulations, excessive restrictions, and the lack of safeguards can hinder the decision of new firms to establish their businesses in an economy. Restrictions can be either general or specific for both domestic and foreign firms. The general ones include restrictions on who can own or lease (based on, for example, firm size, type of business or zoning) and the duration of the lease or ownership. The specific restrictions include conditions on leasing or ownership, such as deposit requirements. Additional restrictions for foreign firms may also include restrictions on the land size, limits on foreign ownership or leasing, and requirements to obtain special investment licenses to own or lease. b. Quality of public services and transparency of information This set of indicators intends to measure: (1) availability of online services and reliability of infrastructure for property transactions, (2) interoperability of services for property transactions, (3) availability of online information on immovable property, (4) availability of online services for building permitting and environmental licensing, (5) interoperability of building permitting systems, and (6) transparency of information for building and environmental licenses. Data for this de facto indicator can be collected via 28 For more information, see the website at: https://www.worldbank.org/en/programs/land-governance-assessment-framework#1. 29 Wehrmann, Babette. 2008. “Land Conflicts: A Practical Guide to Dealing with Land Disputes.” Eschborn, Germany: Deutsche Gesellschaft für Technische Zusammenarbeit. 30 Zakout, Wael, Babette Wehrmann, and Mika-Petteri Törhönen. 2006. “Good Governance in Land Administration Principles and Good Practices.” Food and Agriculture Organization of the United Nations (FAO), Rome, Italy. 31 International Finance Corporation; World Bank; Multilateral Investment Guarantee Agency. 2013. “Good Practices for Construction Regulation and Enforcement Reform: Guidelines for Reformers. Investment climate”. World Bank Group, Washington, DC. https://openknowledge.worldbank.org/handle/10986/16612. 32 The environmental requirements will include all requirements related to constructing a building with a moderate environmental risk. The regulatory standards of green building energy codes will include standards on heating, cooling, hot water, lighting, building envelope, insulation, and fenestration. 14 expert consultations with those involved in real estate transactions, the building permitting process and related environmental clearances. Data collection will be corroborated through administrative data from land registries and municipalities. (1) Availability of online services and reliability of infrastructure for property transactions – To promote efficiency and confidence in the property market, it is important to have adequate infrastructure in place to register property rights. In addition, a reliable land administration system is important for the security of land tenure and the accuracy of ownership and cadastral information. This indicator assesses whether there is an institutional and legal framework to maintain information on land ownership; whether the information on land transactions, ownership, encumbrances, cadastral information is stored electronically; and the geographical coverage of these data. Lastly, this indicator will also assess public access to online services for property and cadastral transactions. (2) Interoperability of services for property transactions – This indicator assesses the exchange of information across property administration institutions, such as land registries and cadasters. Specifically, it assesses whether and how institutional information systems are interlinked to exchange information automatically. For instance, linking or unifying the land registry with the cadastral system has significant advantages. It helps maintain up-to-date records on the legal rights to properties and the spatial characteristics of land plots, thus increasing tenure security and potentially minimizing land disputes. The use of unique identifiers can also ensure data accuracy. Appropriate legislation must be in place to allow such institutional linkage or unification and the issuance of a unique identification number for each property. (3) Availability of online information on immovable property – This indicator assesses the degree of transparency on property ownership and property transactions. Specifically, it measures if the public agencies provide access to information on immovable property transactions. This helps reduce information asymmetry between users and public service providers and increases the efficiency of land markets. Online information availability helps achieve good governance in land administration and has numerous benefits, such as minimizing the possibilities of informal payments. (4) Availability of online services for building permitting and environmental licensing – This indicator assesses the quality of infrastructure at the permit-issuing agency through the availability of online public services, such as the existence of electronic permitting systems to submit building permit applications, other functionalities such as online payment, online notification/tracking, and online issuance of building and occupancy permits. It also assesses the availability of online services for obtaining building-related environmental licenses. (5) Interoperability of building permitting systems – This indicator assesses the exchange of information across agencies, such as municipalities, cadaster, land registries and utility service providers. Specifically, it will assess whether and how institutional information systems are interlinked to exchange information automatically. Linking all relevant agencies has significant advantages as it eliminates the need to submit the same information to multiple public actors, reducing the time for the firm to obtain all the relevant information from each individual agency. Having an integrated Geographic Information System (GIS) can enable building departments and related agencies to streamline and automate their procedures for planning, zoning, and issuing building permits. (6) Transparency of information for building and environmental licenses – This indicator assesses the degree of transparency and accessibility of the building permitting agencies. For instance, it would measure if the permit-issuing agency provides public access to information on the building-related permits. In addition, it would assess public availability of relevant regulations and requirements related to environmental licenses and clearances as well as building energy codes. This helps reduce information asymmetry between public service providers and users and improves accountability by providing easy access to regulations, fees, and payment tracking. 15 c. Efficiency of key services in getting a business location This set of indicators measures the time and cost to complete the different steps an entrepreneur must undergo to purchase a property and obtain building-related permits based on a set of assumptions. Data for this de facto indicator can be collected through expert consultations and would involve professionals who are familiar with property transfers (e.g., lawyers, notaries), building-related permitting processes, and building-related environmental clearances (e.g., architects, engineers). (1) Time and cost to purchase a property – These indicators serve as a proxy for assessing the efficiency of regulations and public services for purchasing a property. They will capture the duration and monetary cost that property lawyers, notaries, or registry officials indicate is necessary to complete critical elements of the registration process (due diligence, signature and registration). (2) Time and cost to obtain building-related permits – These indicators serve as a proxy for assessing the efficiency of regulations and public services for obtaining building-related permits. They will measure the ease of compliance to obtain a building and occupancy permit from the preapproval process until the applications are submitted at the local authority office. (3) Time and cost to obtain environment-related permits – These indicators serve as a proxy for assessing the efficiency of regulations and public services for obtaining all building-related environmental permits and clearances for constructions with moderate environmental risk. 16 C. Utility connections 1. Motivation Entrepreneurs may face substantial burdens to operate their businesses when utility services are unreliable, inefficient, and costly. According to the World Bank Enterprise Surveys, over 30% of businesses globally identified electricity supply as a major constraint to their activities.33 Disruptions in electricity supply negatively impact productivity,34 firm revenues,35 and economic growth.36 Similarly, inadequate water supply – such as ageing infrastructure, poor water quality and changes in water pressure – may also lead to decreased productivity, deterioration of machinery,37 and reduce small and medium-size firms’ profits.38 This is particularly relevant in Sub-Saharan Africa, where around 22% of businesses experience water insufficiencies.39 Overall, losses due to power and water outages have been estimated to reach $82 billion every year for firms in developing economies.40 Access to an affordable and reliable internet is also critical in today’s increasingly digitalized world, where the use of digital technologies can help businesses improve productivity.41 However, as of 2020 the number of fixed broadband subscriptions per 100 people worldwide was still below 20.42 Unreliable networks and the high cost of establishing a broadband connection may prevent companies from adopting and upgrading digital technology in their business operations.43 Regulatory quality and efficiency, the quality and reliability of public services and the cost of compliance with requirements to obtain a connection are important elements of a conducive business environment. Facilitating timely access to resources, at a reasonable cost, and in an environmentally sustainable manner is vital to promote investment and economic growth.44 Regulations and the institutional environment for implementing them affect the performance of infrastructure services. 45 For instance, when electricity connection processes are simpler and less costly, firms tend to perform better.46 At the same time, the choices made by businesses while establishing utility connections affect subsequent energy savings and 33 World Bank. Enterprise Surveys database. http://www.enterprisesurveys.org. 34 Moyo, Busani. 2013. “Power Infrastructure Quality and Manufacturing Productivity in Africa: A Firm Level Analysis.” Energy Policy 61: 1063–1070. 35Allcott, Hunt, Allan Collard-Wexler, and Stephen O’Connell. 2016. “How Do Electricity Shortages Affect Industry? Evidence from India.” American Economic Review 106 (3): 587–624. 36 Andersen, Thomas Barnebeck, and Carl-Johan Dalgaard. 2013. “Power Outages and Economic Growth in Africa.” Energy Economics 38: 19–23. 37 World Bank. 2017. Connecting to Water and Sewerage in Mexico. Washington, DC: World Bank. 38 Selelo, L. R., and Patricia Kefilwe Mogomotsi. 2017. “The Effects of Extended Water Supply Disruptions on the Operations of SMEs.” Southern African Business Review 21: 480–500. 39 World Bank. Enterprise Surveys database. http://www.enterprisesurveys.org. 40 Rentschler, Jun, Martin Kornejew, Stéphane Hallegatte, and Johannes Braese. 2019. “Underutilized Potential: The Business Costs of Unreliable Infrastructure in Developing Countries.” Policy Research Working Paper 8899. Washington, DC: World Bank. 41 World Bank Group. 2016. World Development Report 2016: Digital Dividends. Washington DC: World Bank Group. 42 International Telecommunication Union. 2020. ICT Indicators Database. 43 Chen, Rong. 2019. “Policy and Regulatory Issues with Digital Businesses.” Policy Research Working Paper 8948. Washington, DC: World Bank. 44 World Bank. 2017. Connecting to Water and Sewerage in Mexico. Washington, DC: World Bank. 45 Bergara Mario E., Witold J. Henisz, and Pablo T. Spiller. 1998. “Political Institutions and Electric Utility Investment: A Cross- Nation Analysis.” California Management Review 40(2): 18–35. Cubbin, John, and Jon Stern. 2006. “The Impact of Regulatory Governance and Privatization on Electricity Industry Generation Capacity in Developing Economies.” The World Bank Economic Review 20 (1): 115–141. Zhang, Yin-Fang, Colin Kirkpatrick, and David Parker. 2002. “Electricity Sector Reform in Developing Countries: An Econometric Assessment of the Effects of Privatization, Competition and Regulation.” Centre on Regulation and Competition (CRC) Working Paper 30593. 46 Geginat, Carolin, and Rita Ramalho. 2015. “Electricity Connections and Firm Performance in 183 Countries.” Energy Economics, Elsevier 76: 344–366. 17 safety of supply.47 While aiming to decrease the administrative burden and compliance cost, the regulatory framework should also provide for transparency and set forth quality control, safety and environmental sustainability standards necessary to protect public safety and to ensure adequate quality of public services. Within this context, the BEE project will measure the quality of regulations, provision of public services, and efficiency of implementation of utility regulations and public services, for three key types of utilities – electricity, water, and internet. 2. Indicators in the area of utility connections BEE uses three sets of indicators to measure utility connections: (a) quality of utility regulations (regulatory framework pillar), (b) utility performance and transparency of utility services (public services pillar), and (c) efficiency of implementation of utility regulations and services (the efficacy with which the two pillars are combined in practice). In measuring connections to water, electricity and internet, BEE goes well beyond the scope of Doing Business, which covered only one type of utility, in its Getting Electricity indicator. The BEE indicators also include components measuring safety of utility connections as well as the quality, environmental sustainability, and interoperability of utility services. a. Quality of utility regulations This set of indicators will cover de jure regulatory measures of the legal frameworks governing utility service provision, as well as quality control, safety, and environmental sustainability standards, as applicable. The set of indicators builds on the good practices, guidelines and principles identified by the International Benchmarking Network (IBNET), the International Telecommunication Union (ITU), the African Development Bank48, Regulatory Indicators for Sustainable Energy (RISE) of the World Bank and previous research on good regulatory practices for utility connections conducted by DECIG, amongst others. Data will be collected through consultations with public and private sector experts, including utility providers, regulatory authorities, telecommunication operators, contractors, engineers, electricians, and construction, energy, and telecommunication lawyers. The data will also be corroborated by desk research of relevant laws, regulations, and agencies’ websites. The set of indicators will measure the following two components: (1) Regulatory framework for electricity, water, and internet connections – measures good regulatory practices for the effective and sustainable provision of high-quality utility services. Passive utilities infrastructure, such as poles, ducts, or pipes tends to be expensive and requires a long time to deploy. In this regard, regulations fostering infrastructure sharing, including adherence to a common excavation plan, and obligations for operators owning passive infrastructure to share access at regulated prices can foster efficient deployment of utility services. 49 Regulatory agencies are also important for the provision of utility services since one of their functions is to protect public interests from the exercise of monopoly power, whether through high prices or poor quality, or both.50 Beyond affordability and quality, good regulatory practices account for environmental sustainability.51 In addition, complaint 47 Economidoua, Marina, Valeria Todeschi, Paolo Bertoldi, and Delia D’Agostino. 2020. “Review of 50 Years of EU Energy Efficiency Policies for Buildings”. Energy and Buildings 225 (1). 48 African Development Bank. 2021. Electricity Regulatory Index for Africa 2021. Energy Financial Solutions, Policy and Regulation Department. 49 Martínez Garza Fernández, Ricardo, Enrique Iglesias Rodriguez, and Antonio García Zaballos. 2020. “Digital Transformation: Infrastructure Sharing in Latin America and the Caribbean.” Inter-American Development Bank. 50 Brown, Ashley C., Jon Stern, and Bernard Tenenbaum. 2006. Handbook for Evaluating Infrastructure Regulatory Systems. Washington, DC: World Bank. 51 D’Inverno, Giovanna, Laura Carosi, and Giulia Romano. 2021. “Environmental Sustainability and Service Quality beyond Economic and Financial Indicators: A Performance Evaluation of Italian Water Utilities.” Socio-Economic Planning Sciences 75. 18 mechanisms can help identify bottlenecks in the processes and prompt innovation,52 whereas financial deterrent mechanisms for service failures help set performance standards. These measures can serve as a proxy of adequate regulatory frameworks that can facilitate quality provision of utility services. The component will evaluate laws and regulations governing electricity sector, water services, and provision of internet. Specifically, this component will cover regulations governing infrastructure sharing and rights of way for broadband operators; existence of regulatory agencies overlooking the provision of electricity, water and internet, their functions (for example, role in setting tariffs, service quality targets, monitoring reliability of service supply), as well as key features (such as transparency and independence); availability of independent complaint mechanisms in law or regulation regarding the issues faced by customers related to the provision of electricity and water; existence of financial deterrence mechanisms in law or regulation to promote a reliable supply, and discourage electricity or water supply disruptions, or inadequate or environmentally irresponsible service provision (for example, compensations or penalties). Regulations stipulating performance targets for quality of internet services may also be included, as applicable. The component will also evaluate environmental regulations promoting a sustainable provision of electricity, water, and internet services. These may include smart metering options, wastewater discharge controls, water quality management systems, e-waste management, incentives by utilities for installation and use of energy efficient appliances, renewable energy sources, and water use efficiency. (2) Safety of utility connections – measures good regulatory practices related to quality and safety of connections. While internet connections do not pose similar physical safety risks as water and electricity connections and are subject to more streamlined safety control procedures, safety aspects relevant to the internet relate to cybersecurity in the form of protecting data and communications over the internet as well as the infrastructure of the internet per se.53 Good practices, such as professional licensing and certification, may help reduce information asymmetry and set minimum quality standards.54 In the same vein, inspections ensure installations are compliant with safety and quality regulations.55 These measures could serve as proxies for the strength of safety and quality control of new utility connections. Specifically, this component will cover legally mandated inspections for internal and external water and electricity connections, or requirements for installation works to be carried out by certified contractors; and qualification requirements of professionals assessing plans and feasibility for water and electricity installations and performing or supervising installations, as well as the liability of parties responsible for the installations. The safety of internet connections will cover legally mandated requirements imposed on internet service providers regarding reasonable data security measures aimed at protecting personal information and privacy through intermediary liability, limitations to data collection, redress mechanisms or other relevant legal requirements, as applicable. b. Utility performance and transparency of utility services This set of indicators will cover de facto measures on utility performance, with a focus on monitoring, transparency, and interoperability of utility services. This set of indicators builds on the good practices, 52 Simmons, Richard, and Carol Brennan. 2017. “User Voice and Complaints as Drivers of Innovation in Public Services.” Public Management Review 19 (8): 1085–1104. 53 World Bank Group. 2016. World Development Report 2016: Digital Dividends. Washington DC: World Bank Group. World Bank Group. 2021. World Development Report 2021: Data for Better Lives. Washington, DC: World Bank Group. 54 Leland, Hayne E. 1979. “Quacks, Lemons, and Licensing: A Theory of Minimum Quality Standards.” Journal of Political Economy 87 (6): 1328–1346. 55 Boyne, George, Patricia Day, and Richard Walker. 2002. “The Evaluation of Public Service Inspection: A Theoretical Framework.” Urban Studies (Routledge) 39 (7): 1197–1212. 19 guidelines and principles identified by ITU, The European Benchmarking Co-operation, OECD Principles on Water Governance, UNECE Protocol on Water and Health56, IEEE standards on reliability57, and previous research on good practices in obtaining electricity, internet, and water connections conducted by DECIG, amongst others. The data will be collected through consultations with public and private sector experts, including utilities, regulatory authorities, telecommunication operators, contractors, engineers, electricians, and will be corroborated by desk research of relevant regulations and review of information made publicly available on the relevant agencies’ and operators’ websites. The set of indicators will measure the following three components: (1) Monitoring of key performance indicators on the quality, reliability, and sustainability of utility supply – measures performance indicators governing quality, reliability, and sustainability standards for electricity, water, and internet services. Measuring public service performance data can help establish ‘what works’ in promoting the objectives of the public services, identify the functional competences, and support public accountability.58 Specifically, this component will cover data on the existence of key performance indicators (KPI) to assess the quality, reliability, and sustainability of utility supply, as well as on the public availability of such indicators. Examples of indicators used by utilities and regulators to monitor quality and reliability in each sector include: SAIDI and SAIFI, electricity losses, stability of voltage for electricity services; continuity of water service, water losses, and percentage of water receiving chemical treatment for water services; and download/upload speed of internet connection and latency in the case of internet services.59 (2) Transparency of tariffs and connection requirements – measures the transparency of tariffs for utility services and transparency of connection requirements, serving as a proxy for the predictability of the business environment, especially of firms’ operational costs. Specifically, this component will cover data on transparency and online availability of water, electricity, and internet tariffs, as well as advance notification of tariff changes; and transparency and online availability of required documents, steps, duration, and cost to obtain a new water, electricity, and internet connection. (3) Interoperability of utility services – measures the level of coordination between the agencies involved in the approval processes and integration of utility services from the perspective of customers. The existence of a national infrastructure database is an internationally recognized good practice that can allow for the identification of existing infrastructure before any new project commences,60 and can help expedite information exchange and the approval of utility connection requests. From the customer perspective, the availability of online applications for utility connections and the availability of online payment for bills and connection fees could enhance and facilitate customer experience while receiving utility services. Measures on interoperability of utility services could foster inter- and intra-agency 56 World Health Organization. 2019. UNECE Protocol on Water and Health and the 2030 Agenda: A Practical Guide for Joint Implementation. United Nations Economic Commission for Europe. 57 IEEE Std 1366™-2003. IEEE Guide for Electric Power Distribution Reliability Indices. 58 Bird, Sheila M., David Cox Sir, Farewell Vern T., Harvey Goldstein, Tim Holt, and C. Smith Peter. 2005. “Performance Indicators: Good, Bad, and Ugly.” Journal of the Royal Statistical Society: Series A (Statistics in Society) 168: 1–27. 59 Berg, Sanford V. 2020. “Performance Assessment Using Key Performance Indicators (KPIs) for Water Utilities: A Primer”. Water Economics and Policy 6 (2): 1–19. Federal Communications Commission. 2021. Tenth Measuring Broadband America Fixed Broadband Report: A Report on Consumer Fixed Broadband Performance in the United States. Office of Engineering and Technology. 60 International Telecommunication Union. 2019. Digital Infrastructure Policy and Regulation in the Asia-Pacific Region. 20 information exchange and could serve as an indicator of the level of coordination among agencies and of the efficiency of public services for customers. Specifically, this component will cover the existence of a national infrastructure database and geographic information system incorporating all the network lines of the different utility providers; online applications for water, electricity, and internet; single windows for new water and electricity connections; and single information portals and one-stop shops interconnecting utilities and streamlining approval processes. c. Efficiency of implementation of utility regulations and services This set of indicators will cover de facto measures on efficiency of implementation of utility regulations and of utility service provision. Data for the set of indicators is planned to be collected through firm-level surveys, allowing to obtain representative data on the actual time and cost to obtain the connection, and on service interruption. A representative sample of companies for firm-level surveys could help capture the variation of experience, based on firms’ characteristics, such as size or sector, as well as key parameters of connections, such as voltage capacity for the case of electricity. If firm-level surveys are not feasible, an alternative approach to collect the data for time and cost is through consultations with public and private sector experts, such as contractors, engineers, electricians, utility providers, regulators, and telecommunication operators. In such case, certain basic assumptions about the connections will be included to ensure comparability. The collected data will be corroborated by desk research of regulations, fee schedules and review of websites of relevant agencies and operators. Collection of representative and accurate data on outages through expert consultations, however, might not be feasible. The set of indicators will measure the following three components: (1) and (2) Time & Cost to obtain electricity, water, and internet connections – measure time and cost to receive commercial utility connections, which indicate efficiency of the connection processes, and the ease of accessing utility services by businesses. Providing affordable new connections to electricity has been identified as a way to improve electrification rates in developing economies.61 (3) Reliability of electricity, water, and internet services – measures duration and frequency of power, water, and internet outages, that will reflect businesses’ experience with electricity, water and internet interruptions and will serve as a proxy of user experience of reliability of supply and an indication of how businesses are affected by service failures. 61 Golumbeanu, Raluca, and Douglas Barnes. 2013. Connection Charges and Electricity Access in Sub-Saharan Africa. Washington, DC: World Bank. 21 D. Labor 1. Motivation Labor markets, along with the policies and institutions that shape them, play a key role in private sector development. Employment protection legislation – the regulation of hiring and dismissal of workers – matters for all firms and employees regardless of the sector they operate in. From the perspective of firms, well-designed legislation can help them attract skilled labor and adapt to economic shocks and to changes in economic conditions and technology. From the perspective of employees, employment protection legislation can help them obtain job security in a safe workplace, protection from discriminatory practices as well as social protection. As the world evolves and many countries face a growing workforce and changes in the composition of labor, it is important for countries to update their regulations so that the labor market is inclusive while allowing firms to run their businesses efficiently, while complying with internationally recognized labor standards.62 Many studies point to the association between rigid labor market regulation and higher levels of unemployment (especially among vulnerable groups63) and informality64, along with reduced levels of productivity65 and economic growth.66 Public policies and services matter too. Unemployment insurance schemes, healthcare plans, retirement pensions, public employment services all influence the interaction between employees and employers. Without protection, employed individuals face many risks, including out-of-work poverty.67 However, if protections are too taxing on firms’ budget, they may have unintended negative effects and further encourage informality, as they alter the incentives of employers to hire workers formally. The combination of market flexibility with broad and effective social protection encourages firm formalization and decreases both employer and employee vulnerability to shocks.68 To better assess the labor market, the BEE indicators will capture the segmentation arising from differences in regulations applying to different contractual arrangements (permanent vs. temporary work) or types of workers (migrant vs. non-migrant), and from the lack of enforcement (formal vs. informal sector). BEE will also assess some aspects of labor disputes, as better compliance with mandated benefits makes it attractive to be a formal employee, inducing informal workers to move to the formal sector.69 62 (i) Wandner, Stephen A., David E. Balducchi, and Christopher J. O'Leary. 2018. "Public Employment Policy for an Aging Workforce." Gerontology and Geriatric Medicine 4: 1-13; (ii) Malo, Miguel. 2018. “Finding proactive features in labour market policies: A reflection based on evidence”. ILO Future of Work Research Paper Series. ILO, Geneva. 63 (i) Montenegro, Claudio, and Carmen Pagés. 2003. “Who Benefits from Labor Market Regulations?” Policy Research Working Paper 3143. World Bank, Washington DC.; (ii) Kahn, Lawrence. 2012. “Labor Market Policy: A Comparative View on the Costs and Benefits of Labor Market Flexibility.” Journal of Policy Analysis and Management 31: 94-110; (iii) Kugler, Adriana, Juan F. Jimeno, and Virginia Hernanz. 2005. “Employment Consequences of Restrictive Permanent Contracts: Evidence from Spanish Labor Market Reforms.” Discussion Paper 657. Institute for the Study of labor (IZA), Germany. 64 (i) Sharma, Siddharth. 2009. “Entry Regulation, Labor Laws and Informality.” Working Paper 48927. World Bank, Washington, DC; (ii) La Porta, Rafael, and Andrei Shleifer. 2008. “The Unofficial Economy and Economic Development.” Brookings Papers on Economic Activity 39: 275-352; (iii) Loayza, Norman, Ana Maria Oviedo and Luis Serven. 2012. The Impact of Regulation on Growth and Informality: Cross Country Evidence. Washington, DC: World Bank. 65 (i) Martin, John, and Stefano Scarpetta. 2012. “Setting It Right: Employment Protection, Labour Reallocation and Productivity.” De Economist 160(2): 89-116; (ii) Bassanini, Andrea, Luca Nunziata, and Danielle Venn. 2009. “Job Protection Legislation and Productivity Growth in OECD Countries.” Economic Policy 24(58): 349-402. 66 Loayza, Norman, Ana Maria Oviedo and Luis Serven. 2012. The Impact of Regulation on Growth and Informality: Cross Country Evidence. Washington, DC: World Bank. 67 Acemoglu, D., 2001. “Good jobs versus bad jobs.” Journal of Labor Economics 19(1): 1-21. 68 Loayza, Norman. 2018. “Informality: Why Is It So Widespread and How Can It Be Reduced?” World Bank Research and Policy Briefs, World Bank, Washington DC. 69 Almeida, Rita, and Pedro Carneiro. 2012. “Enforcement of Labor Regulation and Informality.” American Economic Journal: Applied Economics, 4(3): 64-89. 22 2. Indicators in the area of Labor BEE uses a set of three indicators in the area of labor: (a) the quality of labor regulations (regulatory pillar); (b) the adequacy of public services for the labor market (public services pillar); and (c) the ease of employing labor which assesses how the two pillars (regulatory and public services) contribute in practice to the efficient functioning of labor markets from the perspective of both the firm and the employee. The indicators will measure labor regulations and public services as they apply to different types of workers in different contractual arrangements, including but not limited to permanent, fixed-term employment, self- employed, and foreign workers. This is to understand how the policy and practice vary depending on the type of workers, as well as how countries address labor market segmentation. In contrast to the former Doing Business Employing Workers topic70, BEE will consider more explicitly the perspective of employees. It will offer a more balanced view, by including indicators on workers’ protection (unemployment insurance, healthcare, pension), decent working conditions (rights at work, social dialogue, and others) and public services, in addition to the data on labor market flexibility. Another important addition is the efficiency component which will collect data directly from firms to understand how rules and regulations are applied in practice. Finally, unlike Doing Business the BEE indicators will include different types of firms and workers, including workers on different types of employment contracts. a. Quality of labor regulations This set of de jure indicators will measure the regulation of employment, applying to businesses, in terms of (1) workers’ protection, and (2) restrictions on hiring, working hours and redundancy. Data for these de jure indicators will be collected through expert consultations with labor lawyers. No case study will be used to collect these data, but some assumptions may be included to ensure comparability of data across countries. (1) Workers’ protection – This indicator assesses whether the applicable regulatory framework includes good practices promoting a safe, secure, and non-discriminating workplace environment. Economies where employees feel protected, and their rights respected, tend to have higher levels of productivity.71 The workers’ protection indicator will measure regulations that guarantee employee protection and decent working conditions in accordance with international labor standards. These areas will cover the availability of minimum wage and equal remuneration for work of equal value, non-discrimination at the workplace (race, color, religion, sex, age, or national origin), workers’ right to organize and collective bargaining, safe and healthy working conditions, and the right to annual leave and family leave. This indicator will build on applicable International Labor Standards drawn up by the ILO, in relation also to the 2030 Agenda for Sustainable Development and previous research on good practices conducted by the World Bank Group individually, and in cooperation with OECD, ILO, and other institutions.72 (2) Employment restrictions – This indicator will assess flexibility in hiring, work scheduling, and dismissal of employees. Restrictions in the regulation of employment can prevent businesses to respond to changes and economic shocks, lead to misallocation of companies’ resources and leave some categories of workers vulnerable (young, female or less experienced workers, in particular). This 70 Employing Workers used to be part of Doing Business. Over 10 years ago it was removed from the aggregate rankings, while the data continued to be collected and included as an Annex. In 2020 it was made a standalone project: www.worldbank.org/employing-workers. 71 World Bank. 2012. World Development Report 2013: Jobs. World Bank, Washington, DC. 72 ILO. 1998. “ILO Declaration on Fundamental Principles and Rights at Work” Recommendation and Resolutions adopted by the International Labour Conference, 86th Session, Geneva. 23 indicator will build on OECD, IMF, and World Bank research on labor market flexibility. 73 The flexibility in hiring will be measured across different types of contracts and probationary periods. Working hours will be measured through working hours per day/week, restrictions, and premiums for work during irregular working hours, such as night work or work on rest days. Rules and statutory cost on dismissals will be measured through notification and approval requirements, as well as through the regulation of notice period and severance payment. b. Adequacy of public services for the labor market This set of indicators will provide selected de facto measures of public services affecting the private sector with respect to: (1) workers’ social protection, (2) public employment services and (3) individual labor dispute resolution. Data for these indicators will be collected through expert consultations with labor lawyers, labor bureaus, and labor ministries, and can be corroborated by desk research. (1) Workers’ social protections – This indicator will assess aspects of social protections available to workers, with a focus on unemployment insurance, healthcare, and pension. For instance, it will determine the availability, type and level (e.g., duration and amount) of unemployment insurance, regardless of the type of contract, Similarly, the indicator will assess the availability of health care and pension as an employee benefit for different types of workers, including access of informal workers to social security. (2) Public employment services – This indicator will assess public employment services that promote participation in the labor force and help workers match to employment opportunities, including but not limited to employment services, job search assistance, job training programs, and employment subsidies. The indicator will also measure the extent of digitalization of public employment services through the assessment of digital job-seeking platforms. These platforms can take different forms, including online vacancy databases or workforce sharing platforms that connect businesses through a temporary workforce exchange.74 (3) Individual labor dispute resolution – This indicator will assess the availability of public services provided for resolution of individual labor disputes arising from day-to-day workers’ grievance and complaints.75 It will also assess the availability of administrative bodies and/or government programs that educate workers about their rights. This will serve as a proxy for the quality and efficiency of public institutions, such as labor courts/tribunals and/or administrative bodies (i.e., labor commissions, inspectorates, departments of labor) that provide consultations, administrative guidance and settlement of labor disputes between employers and employees. 73 (i) Froy, F., et al. 2011, "Building Flexibility and Accountability Into Local Employment Services: Synthesis of OECD Studies in Belgium, Canada, Denmark and the Netherlands", OECD Local Economic and Employment Development (LEED) Papers 2011/10. OECD, Paris; (ii) Bernal-Verdugo, Lorenzo E., Furceri, Davide, and Guillaume, Dominique M. 2012. “Labor Market Flexibility and Unemployment: New Empirical Evidence of Static and Dynamic Effects”. IMF Working Paper 12/64. IMF, Washington, DC; (iii) Betcherman, Gordon. 2014. “Labor Market Regulations: What Do We Know about Their Impacts in Developing Countries?” Policy Research Working Paper 6819. World Bank, Washington, DC. 74 European Commission: Directorate-General for Employment Social Affairs and Inclusion European Network of Public Employment Services. 2020. “PES measures and activities responding to Covid-19. Survey-based study”, European Union. 75 ILO Recommendation No. 130 (1967) states that a complaint may arise over “any measure or situation which concerns the relations between employer and worker or which affects or may affect the conditions of employment of one or several workers in the undertaking when that measure or situation appears contrary to provisions of an applicable collective agreement or of an individual contract of employment, to works rules, to laws or regulations or to the custom or usage of the occupation, branch of economic activity or country, regard being had to principles of good faith”. 24 c. Ease of employing labor This is a set of de facto indicators that will measure how efficiently labor regulation and public services are implemented in practice, informing on the realization of the policy objectives (e.g., flexibility for businesses, protection of basic rights for employees, and access to the job market for the unemployed). More specifically, by relying on the experience of firms and expertise of local practitioners, it will measure the enforcement of labor and social protection laws as well as the efficiency and coverage of public employment services for job seekers. The indicators will also assess the de facto availability and frequency of labor inspections as well as the efficiency of public employment centers. Questions about compliance with working hours, non-wage costs, and labor inspections will be addressed to firms because such questions directly relate to their everyday operations. Hence, firms are better positioned to provide high-quality data in these areas. Questions on discrimination, flexibility of hiring and dismissals, as well as the efficiency of public employment services will be collected through expert consultations with labor lawyers. This is because firms may either be reluctant to respond due to the delicate nature of an issue (discriminatory practices) or simply have little experience to comment on certain topics (quality of training programs for unemployed). In such cases, we assume that expert consultations would be a more reliable source of data. 25 E. Financial services 1. Motivation Even the most brilliant business idea can remain just that – an idea – with the lack of proper financing. Access to finance remains a major constraint for almost a quarter of firms worldwide,76 despite being essential for a firm’s operations, being positively associated with firm innovation, 77 and directly contributing to a firm’s resilience – which was especially accentuated during the recent pandemic. 78 Moreover, research has shown that private sector financing in developing economies has positive macroeconomic effects as employment rates can benefit from firms’ improved access to finance.79 Access to finance depends on several factors such as the macroeconomic conditions and the level of development of the financial markets and infrastructure. The regulatory framework and the availability of information services also affect the operation of credit markets and the likelihood that firms will obtain financing. Access to finance may be restrictive when only immovable assets can act as collateral. Countries with a modern secured transactions system, where movable assets are commonly used as collateral, offer more access to credit to borrowers at affordable rates.80 Moreover, to enable financing, lenders require adequate access to borrowers’ credit information to overcome information asymmetries. Sharing such information in the form of credit reporting reduces lenders’ uncertainty about borrowers’ total debt exposure, increases the availability of credit and lowers interest rates.81 Accessible financing plays an important role in maintaining a company’s financial stability. Removing bottlenecks associated with making and receiving payments further strengthen firms’ financial security. In recent years, electronic payments have become more widespread for different types of government payments and collections.82 However, the ever-increasing digitization of the economy requires proper regulation of electronic monetary solutions to reap the benefits of technological progress. This would enable the extensive use of electronic payments, which is associated with reduced tax evasion83 and lower informality84 in the private sector. 76 World Bank. Enterprise Surveys database: https://www.enterprisesurveys.org/en/enterprisesurveys. 77 Wellalage, Nirosha Hewa, and Stuart Locke. 2020. “Formal Credit and Innovation: Is There a Uniform Relationship across Types of Innovation?” International Review of Economics & Finance 70: 1-15. Wellalage, Nirosha Hewa, and Viviana Fernandez. 2019. “Innovation and SME Finance: Evidence from Developing Countries.” International Review of Financial Analysis 66: 101370. Qi, Shusen, and Steven Ongena. 2019. “Fuel the Engine: Bank Credit and Firm Innovation.” Journal of Financial Services Research 57(2): 115-147. 78 Amin, Mohammad, and Domenico Viganola. 2021. “Does Better Access to Finance Help Firms Deal with the COVID-19 Pandemic? Evidence from Firm-Level Survey Data.” Policy Research Working Paper 9697. Washington, DC: World Bank. Hu, Shiwei, and Yuyao Zhang. 2021. “COVID-19 Pandemic and Firm Performance: Cross-country Evidence.” International Review of Economics & Finance 74: 365-372. 79 Meghana Ayyagari, Pedro Juarros, Maria Soledad Martinez Peria, and Sandeep Singh. 2021. “Access to Finance and Job Growth: Firm-Level Evidence across Developing Countries.” Review of Finance 25 (5): 1473-1496. Siemer, Michael. 2019. “Employment Effects of Financial Constraints during the Great Recession.” Review of Economics and Statistics 101: 16-29. 80 World Bank Group. 2015. Credit Reporting: Knowledge Guide (English). Washington, DC: World Bank Group. 81 Brown, Martin, Tullio Jappelli, and Marco Pagano. 2009. “Information Sharing and Credit: Firm-Level Evidence from Transition Countries.” Journal of Financial Intermediation 18: 151-172. Martinez Peria, Maria Soledad, and Singh, Sandeep. 2014. “The Impact of Credit Information Sharing Reforms on Firm Financing.” Policy Research Working Paper 7013. Washington, DC: World Bank. 82 World Bank Group. 2020. Payment Systems Worldwide: Summary Outcomes of the Fifth Global Payment Systems Survey: A Snapshot (English). Washington, DC: World Bank Group. 83 Immordino, Giovanni, and Francesco Flaviano Russo. 2018. “Cashless Payments and Tax Evasion.” European Journal of Political Economy 55: 36-43. 84 Këlliçi, Erdet, and Indrit Baholli. 2015. “Mobile Payments, Driving Economies in Development Countries Toward Less Risky Transactions and Lowering Informality.” European Academic Research 3 (1): 572-588. 26 2. Indicators in the area of financial services BEE uses three sets of indicators in the area of financial services: (a) the quality of regulations for secured transactions, e-payments, and green financing (regulatory pillar); (b) the quality of credit reporting framework, including scope and availability of credit information distributed through credit bureaus and registries, as well as availability and functionality of a collateral registry (public services pillar); and (c) the ease of receiving financial services (combination of regulatory and public services pillars). While the area of financial services can be very broad and different types of firms may hold interest in different types of financing, the selected measures are identified as broadly relevant to private sector as a whole, irrespective of companies’ size, legal structure, ownership, and other specific factors. The Financial Services topic incorporates the Doing Business Getting Credit topic and adds four new components. The quality of regulations for secured transactions component remains the same as it was in Doing Business. The quality of reporting framework for operationalization of credit bureaus and registries additionally captures the data exchange between credit reporting service providers (CRSPs) and potentially reassesses the criteria for scoring eligibility 85 when multiple CRSP operate. Similarly, the quality of reporting framework for operationalization of collateral registries component introduces the data for the cost of recording a collateral, the frequency of updates, and potentially usage data (subject to availability). The remaining four components (quality of regulations for electronic payments, quality of regulations for green financing, ease of obtaining a loan, and ease of making an e-payment) are new and are not based on Doing Business methodology. Each of these measures are discussed in detail below. a. Quality of regulations for secured transactions, e-payments, and green financing This indicator set will measure the quality of regulations (de jure elements) for secured transactions, e- payments, and green financing in each economy, and how they compare to internationally recognized good practices. The following will be the indicator set’s three components: (1) Secured transactions – The quality of regulations for secured transactions assesses the existence of an integrated legal framework (i.e., rules around the possibility for debtors to grant movable assets as collateral without giving up possession of the asset) and the rules regarding the enforcement of security interests in movable assets. This indicator set component also examines the rights and obligations of all types of creditors and debtors with regards to the use of movable assets as collateral. It has two de jure sub-components, data for which will be collected through expert consultations (for example, financial lawyers and commercial banks) complemented by the reading of the law. The first sub-component measures whether an integrated and functional approach to secured transactions exists following the good practices set by the United Nations Commission on International Trade Law (UNCITRAL) Legislative Guide on Secured Transactions and other internationally accepted standards. It will look at security rights in all types of movable assets, and whether collaterals can be created in both current and future assets. It will also analyze the rules regarding incorporated and non-incorporated entities creating or acquiring collateral in movable assets (i.e., from the perspective of both debtors and creditors). It will also identify the obligations/debts that can be secured by such collateral. The second sub-component focuses on the enforcement of security interests in movable assets. It will assess, upon default of the debtor, which creditor would have priority in obtaining the full or part of the collateral when there are competing claims on that same asset outside insolvency procedures. It will 85 BEE will explore recording CRSPs features as long as they are applicable to any of the credit bureau or registries operating in the economy that meet a certain coverage threshold. Such coverage threshold will be defined at a later stage. 27 also analyze the possibility of agreeing to out-of-court enforcement of the security interest and to both seize and sell the encumbered asset through public and/or private auction or, if agreed, that the secured creditor would take the asset in satisfaction of the obligation. (2) Electronic payments – Although relatively new, electronic payments are becoming increasingly widespread as they allow faster and more flexible transactions. Furthermore, digital transactions enable an entire novel type of businesses that operate in e-commerce and help stimulate economic growth.86 At the same time, e-payments do not exist in a vacuum and are a part of a larger payments system. Therefore, while BEE focuses on e-payments, the data will also include aspects that are applicable for banking and traditional payments in general. Electronic payments commence with a payment order issued using a digital device and involve several parties: the payer and the recipient, as well as payment processors that act as service providers. Sound regulatory framework around e-payments that promotes financial inclusion is based on the following principles:87 (i) robust risk management (including through the supervision/oversight of the service providers); (ii) protection of customer funds (including regulation of erroneous and fraudulent transactions); (iii) transparency of fees, terms, and conditions; (iv) availability of solid recourse and dispute resolution mechanism; (v) wide accessibility that does not hinder the integrity of financial system (including interoperability requirements and non-exclusivity conditions); (vi) and promotion of competition among the service providers, instruments, products, business models and channels. Data will be assessed through these six principles. This component focuses on good regulatory practices in domestic e-payments although typically such a legal framework would extend to cross-border e- payments as well. Data for this de-jure component will be collected through expert consultations (for example, financial lawyers and commercial banks) complemented by the reading of the law. (3) Green financing – Green financing acts as a catalyst of an environmentally sustainable economy by shifting investments into green technology and sustainable projects (for instance, renewable energy, recycling, green infrastructure). 88 The Network for Greening the Financial System stresses the importance of green financing instruments (such as green bonds and green loans) in the transition toward sustainable finance. 89 The proliferation and use of these instruments have significantly expanded in the recent years in response to addressing sustainable development goals (SDGs). For example, the green bonds market is estimated to be worth $2.36 trillion by 2023.90 The use of green bonds improves a firm’s operational and equity performance, green innovations, value creation, investment potential, stock returns and liquidity.91 This component will measure: (i) sustainable finance regulation following the framework developed by the UNEP Inquiry and the Green Finance Platform;92 (ii) good practices related to green bonds 86 Zandi, Mark, Virendra Singh, and Justin Irving. 2013. “The Impact of Electronic Payments on Economic Growth.” Moody’s Analytics: Economic and Consumer Credit Analytics 217(2). 87 World Bank Group. 2020. Payment Aspects of Financial Inclusion in the Fintech Era. Washington, DC: World Bank Group. World Bank Group. 2020. Digital Financial Services. Washington, DC: World Bank Group. 88 Gilchrist, David, Jing Yu, and Rui Zhong. 2021. “The Limits of Green Finance: A Survey of Literature in the Context of Green Bonds and Green Loans.” Sustainability 13(478). 89 Network for Greening the Financial System (NGFS). 2019. A Sustainable and Responsible Investment Guide for Central Banks’ Portfolio Management. NGFS Secretariat. 90 World Economic Forum. 2020. “What Is Green Finance and Why Is It Important?” https://www.weforum.org/agenda/2020/11/what-is-green-finance/. 91 Tang, Dragon Yongjun, and Yupu Zhang. 2020. “Do Shareholders Benefit from Green Bonds?” Journal of Corporate Finance 61: 101427. 92 Green Finance Platform. 2021. Green Finance Measures Database. Technical Note: https://www.greenfinanceplatform.org/sites/all/themes/f1omega/f1gfp/images/Technical%20Note%20-%20GFMD.pdf. 28 issuance, such as those defined by the Sustainability Bond Guidelines published by the International Capital Markets Association;93 (iii) the significance of green bonds issuance in the bond market; and (iv) the requirements of transparency, professional qualifications, and instruments in place for avoiding conflicts of interest applying to companies acting as external reviewers for green bonds. Data for this de jure component will be collected via expert consultations with finance lawyers and corroborated by desk research through the reading of laws and regulations. b. Quality of credit reporting framework This indicator set will measure the quality of the credit reporting framework, which seeks to reflect the de facto elements in each economy and focuses on relevant proxies measuring the functioning of institutions providing public services. In that sense, the indicator set will assess how CRSPs, such as credit bureaus or credit registries, and collateral registries operate. The indicator set will have two components: (1) Operationalization of credit bureaus and registries – Credit bureaus and registries94 collect data on the credit history of individuals and firms and share it in the form of credit reports and additional services to improve the efficiency of the lending process, by reducing information asymmetries. By accessing borrowers’ credit information, lenders can better understand lending risks associated with each potential borrower. The quality of the credit reporting framework measures the availability of CRSPs and the scope of the data and services they offer. This component of the indicator set measures whether an operational and modern credit bureau or credit registry is operational and provides data on the borrowing history of individuals and firms through credit reports. It evaluates whether the CRSPs: (i) provide sufficient information to inform lending decisions (positive and negative data, a minimum amount of historical data); (ii) complement traditional finance data (banks and other financial institutions) with alternative data (telecom, retailers, utilities, rent) that help borrowers with limited credit history to build their records; and (iii) follow good practices regarding the rights of borrowers to access their own financial records (the right to consult own credit reports for free, the possibility of receiving notifications of negative information being reported to the credit bureau or registry, and the right to rectify data in case of discrepancies). In addition, the component collects information on the data exchange between different CRSPs, and the availability of value-added services, such as credit scores, that facilitate the evaluation of the creditworthiness of potential borrowers. To capture the extent of usage of the credit information services, standardized95 data on the share of issued credit reports will be published for information purposes. Because of its nature, the component combines de jure and de facto data. For example, for borrowers’ rights to access their own credit data, two criteria must be met: (i) borrowers have a specified legal right to access their data, and (ii) such access is available in practice and affordable.96 Data for this component will be collected through consultations with CRSPs. (2) Operationalization of collateral registries – Collateral registries are publicly available databases of interests in moveable assets by incorporated and nonincorporated entities. They support the legal 93 International Capital Markets Association. 2021. Green Bond Principles. https://www.icmagroup.org/sustainable-finance/the- principles-guidelines-and-handbooks/sustainability-bond-guidelines-sbg/. 94 Credit bureaus and registries differ in terms of their ownership with the former generally being privately owned companies and the latter established by the government in the majority of cases, usually under the management of the central bank or the banking supervision authority. Regardless of the ownership structure, as CRSPs both types of organizations can serve the same role by providing information on borrower’s histories that assist creditors in their lending decisions. 95 Since economies have different population and CRSPs coverage rates, the usage data will be normalized by calculating the average number of reports issued on one borrower covered by the CRSP. In combination with the coverage rate (expressed as a percentage of adult population) these data will allow to understand the extent to which CRSP services are used. 96 Following the Doing Business approach, access is considered affordable if it costs less that 1% of GNI per capita. 29 framework of security rights in movable assets by facilitating awareness of both their existence and establishing priority based on the time of registration.97 Functioning collateral registries further enable lenders to assess risks when the borrower intents to secure the credit with collateral assets. The component assesses whether a collateral registry is in operation, whether it is unified geographically, and whether it has an electronic database indexed by debtors’ names. The assessment considers if the registry is noticed-based – a registry that files only a notice of the existence of a security interest (not the underlying documents) and does not perform a legal review of the transaction; if the registry also publicizes functional equivalents to security interests; and if it has modern features such as those that allow secured creditors (or their representatives) to register, search, amend or cancel security interests online. Furthermore, to ensure access and usage of the collateral registry and the timely publicity of security interests, the component collects information on the fees and costs associated with the registration of security interests. It also records the frequency of the system updates to reflect such registrations as a proxy for the time it takes to register (since the good practice is to have a notice-based registration which implies an instantaneous process). The component may collect data on the level of usage, through the volume of the registration records. These de facto data will be collected through expert consultations (for example, financial lawyers and commercial banks). c. Ease of receiving financial services This indicator set will measure the time and cost (de facto elements) to obtain a loan and make an e-payment in each economy. This measure of efficiency serves as a proxy for the efficiency of receiving financial services. The following will be the indicator set’s two components: (1) Making an e-payment – This de facto component measures the time and cost required to make an electronic payment through each of the following four methods: internet banking, mobile banking, e- money, and payment cards. Each of these four types of payments will be assessed twice: assuming a business-to-business (B2B) transaction and assuming a person-to-business (P2B) transaction. The time estimate will capture the entire process – from the moment of submitting a payment to its full clearance and complete release of funds (i.e., until the recipient has received and is able to use the funds). The cost will be recorded as a share of the transaction amount. Data will be collected using firm-level surveys. (2) Obtaining a loan – This de facto component measures the time and cost required for a firm to obtain a loan. Firm-level surveys will provide factual data on loans that firms have recently obtained. To allow for comparability, the collected data will provide additional information regarding key characteristics of the loans, such as the source of financing, the purpose of the loan, the period and amount of the loan, whether collateral was used, etc. The component will focus on domestic loans provided by commercial banks, and it may collect data on loans received from both public and private banks. The component will capture the time to prepare the loan application (including the time to obtain a credit report, gather financial records, secure collateral or a personal guarantee and fill out the application forms) and the time for the application to be evaluated and approved by the lender. The cost for obtaining a loan will include components such as the applicable fees and any additional expenses to secure the loan. The cost will be recorded as a share of the loan. Both time and cost will be normalized to account for variation in the loan value and repayment times. 97 Alvarez de la Campa, Alejandro. 2011. “Increasing Access to Credit through Reforming Secured Transactions in the MENA Region.” Policy Research Working Paper 5613. Washington, DC: World Bank. 30 F. International trade 1. Motivation International trade is a key driver of economic growth and plays a decisive role in the promotion of private sector development. The private sector is impacted by an economy’s openness to international trade through a multitude of channels, as covered by an extensive body of literature. The first of these channels lies at the origin of trade theory, as engaging with the global market brings about increased competition with foreign firms, both domestically and abroad, which leads to domestic firm specialization in areas of comparative advantage and the reallocation of resources to the most productive firms.98 To remain competitive, firms need to continuously adapt, innovate, and improve their efficiency, resulting in aggregate productivity growth. Trade openness generates further productivity gains as it allows firms to overcome the limitations of their domestic markets, creating economies of scale, and providing access to cheaper intermediate inputs of higher quality and higher variety.99 In addition, international trade flows enable domestic firms to take advantage of knowledge and technology transfers as they interact in the global market.100 Lastly, research also shows that firms that participate in international trade tend to be larger and more productive.101 An enabling environment for the private sector must, thus, be conducive for firms to actively compete in the global economy by minimizing trade related costs. In the complex context of international trade, there are several aspects of the business environment that may affect firms’ participation and performance in the global market. First, the regulatory framework may serve as a powerful catalyst to participate in international trade. In the era of the global economy, and especially after the digital acceleration caused by the COVID-19 pandemic, firms’ competitiveness depends on whether the regulatory framework can adapt to the evolving context and establish a transparent, predictable, and safe environment for the potential of trade, including e-commerce, to be harnessed. Conversely, restrictive regulations create market distortions, such as those imposed by stringent non-tariff measures, fees, or redundant processes, and have a negative impact on trade.102 Moreover, international trade regulations may fulfill an important role in promoting green goods and technologies that aim to mitigate climate change and reduce greenhouse gas emissions. Second, governments can provide public services to streamline trade procedures and allow the private sector to maximize the benefits and/or minimize the restrictions provided by regulations. These trade facilitation efforts increase participation in international trade for both small and large firms.103 Finally, the time and costs borne by the private sector when complying with trade regulations and using the implemented public services may hinder its ability to access the global market, representing a substantial barrier to trade.104 2. Indicators in the area of international trade BEE uses three sets of indicators in the area of international trade: (a) the quality of regulations for international trade in goods, e-commerce and environmentally sustainable trade (regulatory framework pillar), (b) the quality of public services for the facilitation of international trade in goods (public services 98 Melitz, M. J. 2003. “The Impact of Trade on Intra-Industry Reallocations and Aggregate Industry Productivity.” Econometrica, 71 (6): 1695–1725. 99 Goldberg, P. K., Khandelwal, A. K., Pavcnik, N., and Topalova, P. 2010. “Imported Intermediate Inputs and Domestic Product Growth: Evidence from India.” The Quarterly Journal of Economics, 125 (4): 1727–1767. 100 Madsen, J. B. 2007. “Technology Spillover through Trade and TFP Convergence: 135 Years of Evidence for the OECD Countries.” Journal of International Economics, 72 (2): 464–480. 101 Bernard, A. B., Jensen, J. B., Redding, S. J., and Schott, P. K. 2007. “Firms in International Trade.” The Journal of Economic Perspectives, 21 (3): 105–130. 102 Fernandes, A. M., Ferro, E., and Wilson, J. S. 2019. “Product Standards and Firms’ Export Decisions.” World Bank Economic Review, 33 (2): 353–374. 103 Fontagné, L., Orefice, G., and Piermartini, R. 2020. “Making Small Firms Happy? The Heterogeneous Effect of Trade Facilitation Measures.” Review of International Economics 28 (2020): 565–598. 104 Hummels, David L., and Schaur, G. 2013. “Time as a Trade Barrier.” American Economic Review, 103 (7): 2935–59. 31 pillar), and (c) the efficiency of importing goods, exporting goods, and engaging in e-commerce (the efficacy with which the two pillars are combined in practice). While BEE focuses on international trade in goods, it acknowledges that trade in services is an increasingly important component of international trade. However, considering the resources required to cover this aspect and those available to BEE, there is no current plan to measure international trade in services. Indicators on international trade in services may be added at a later stage of the project. The BEE indicators differ from the Doing Business Trading across Borders topic in two main facets. First, whereas Doing Business focused on the ease to comply with trade regulations, the BEE indicators will expand the scope of the topic to include the quality of the regulatory framework, as well as the quality of public services provided by governments. Furthermore, as detailed below, other areas, such as e-commerce and environmentally sustainable trade, will also be included pertaining to BEE’s focus on the cross-cutting themes of adoption of digital technologies and environmental sustainability. Second, the International Trade topic will not be limited to a case study with standardized scenarios and specific assumptions. The data will be collected through expert consultations for the regulatory framework and public services pillars, and through representative firm-level surveys for the efficiency indicators. The BEE methodology will thus expand the level of representativeness of the data, without tying it to specific assumptions on traded products, trading partners, mode of transport and border. a. Quality of regulations for international trade in goods and e-commerce Uncertainty about trade procedures, future conditions, and application of existing regulations generates increased risk, aggravates transaction costs, and delays investments.105 Good practices in the regulatory framework for international trade are fundamental to creating a stable and predictable trading environment. Additionally, on the rising area of e-commerce, effective policies and regulations are required to remove obstacles to cross-border online trade, foster inclusive private sector growth, and at the same time ensure the necessary safeguards and address potential adverse effects. At the same time, trade policies may also include restrictive trade measures. These may be important to protect public safety, health, and the environment, but can become counterproductive and hinder trade if they are excessive106 or if they are ineffectively implemented by the public sector. Governments, thus, need to design effective regulations that strike the right balance between safety and health, and streamlined trade procedures. This is especially relevant for non-tariff measures, such as sanitary and phytosanitary regulations, standards, and technical regulations, which have steadily risen in importance as key barriers to trade, while tariffs declined, despite the recent trade wars.107 A similar approach should be applied to regulatory restrictions on e-commerce, such as specific bans on online sales. This set of indicators will cover five components which will serve as proxies for assessing the legal framework governing international trade and e-commerce, showcasing the commitment to open trade policies that ensure a safe and level-playing field, promote competition, reduce digital divides, and mitigate climate change. The quality of regulations will be assessed through the selection of internationally recognized good practices, as detailed below. Data for this de jure indicator will be collected via expert consultations with trade economists, trade lawyers, and e-commerce lawyers, and can be corroborated by desk research through readings of the law. 105 Handley, K. 2014. “Exporting under Trade Policy Uncertainty: Theory and Evidence.” Journal of International Economics, 94 (1): 50–66. 106 Fontagné, L., Orefice, G., Piermartini, R. and Rocha N. 2015. “Product Standards and Margins of Trade: Firm-level Evidence.” Journal of International Economics, 97 (1): 29–44. 107 Hoekman, B. and Nicita, A. 2011. “Trade Policy, Trade Costs, and Developing Country Trade.” World Development, 39 (12): 2069–2079. 32 (1) Good regulatory practices enabling international trade – assesses whether the regulatory framework promotes a transparent and predictable trading system by providing legal obligations that mandate public access to the rules and regulations pertaining to international trade, and laws and regulations to ensure fair and predictable international trade processes. Good regulatory practices established in the World Trade Organization’s (WTO) Trade Facilitation Agreement (TFA), the World Customs Organization’s (WCO) Revised Kyoto Convention, the United Nations Economic Commission for Europe (UNECE) Recommendations on Information Trade Portals and on Establishing a Legal Framework for International Trade Single Window, and the WBG Guide on Developing a Trade Information Portal, among others, may serve as guidelines to benchmark these areas. (2) Good regulatory practices enabling e-commerce – assesses whether the regulatory framework promotes a safe and trusted environment for e-commerce by providing legal protection to e-commerce users and service providers, legal requirements to promote electronic commerce transactions, and cybersecurity requirements to ensure information security. Good regulatory practices established in the UNCITRAL’s Model Laws on Electronic Commerce, on Electronic Transferable Records, on Electronic Signatures, and the Technical Notes on Online Dispute Resolution, the United Nations Convention on the Use of Electronic Communications in International Contracts, as well as the OECD Recommendation on Consumer Protection for E-commerce and the OECD Guidelines on the Protection of Privacy, among others, may serve as guidelines to benchmark these areas. (3) Good regulatory practices enabling environmentally sustainable trade – assesses whether the regulatory framework promotes carbon footprint reduction by establishing Border Carbon Adjustments (BCAs) and lower tariffs on environmental goods. BCAs are import fees levied by carbon-taxing countries on goods manufactured in non-carbon-taxing countries. Well-designed BCAs enable early mover countries to implement higher carbon prices than their trading partners in a manner that limits losses in competitiveness, addresses carbon leakage, and incentivizes mitigation actions in other countries. 108 Likewise, lowering tariffs on environmental goods improves access to products and technologies that support the move to a low carbon future.109 (4) Regulatory restrictions on international trade – assesses whether the regulatory framework establishes restrictive trade policies, including non-tariff measures, and mandatory licensing and membership requirements for trade actors. Regarding the former, while the United Nations Conference on Trade and Development (UNCTAD) has collected data on non-tariff measures since 2012, covering over 100 countries, BEE would add value by providing data for selected groups of measures and sectors and covering a larger sample of countries through a cyclical benchmarking exercise. Good regulatory practices established in the WTO Agreement on Sanitary and Phytosanitary Measures and the Technical Barriers to Trade Agreement, among others, may serve as guidelines to benchmark these areas. (5) Regulatory restrictions on e-commerce – assesses whether the regulatory framework establishes restrictive or discriminatory measures, such as bans on online sales, standards on cross-borders data flows, and taxation measures. b. Quality of public services for the facilitation of international trade in goods The provision of public services to facilitate trade and reduce the cost to comply with trade regulations is a prominent matter in the international trade agenda, including being at the center of the WTO TFA. Trade 108 Parry, I., Dohlman, P., Hillier, C., Kaufman, M., Kwak, K., Misch, F., Roaf, J., and Waerzeggers, C. 2021. “Carbon Pricing: What Role for Border Carbon Adjustments?” IMF Staff Climate Note 2021/004. Washington, DC: International Monetary Fund. 109 Shapiro, J. 2020. “The Environmental Bias of Trade Policy”. The Quarterly Journal of Economics 136 (2): 831–886. 33 facilitation efforts encompass four pillars, namely transparency, predictability, simplification, and harmonization and standardization, and aim at streamlining trade procedures to minimize compliance costs. These efforts span diverse areas of public services, which include, among others, trade information portals, electronic trade single windows, risk assessment systems, Authorized Economic Operators (AEO) programs, increased cooperation and coordination between customs and other border agencies (both at the domestic level and cross-border), participation in bilateral and regional trade agreements, and improvements to the quality of trade infrastructure and connectivity. Crucially, their implementation in practice is associated with a decrease in operational and transaction costs and an increase in trade flows.110 This set of indicators will cover six components which will serve as a proxy for the overall implementation of trade facilitation measures across all pillars. These components expand on the OECD Trade Facilitation Indicators whose assessment mirrors the provisions of the TFA. The quality of public services will assess which features have been implemented and made available to the trading community. Data for this de facto indicator will be collected via expert consultations with freight forwarders, customs brokers, shipping lines, port authorities, as well as customs and other agencies, and can be corroborated by desk research. (1) Transparency and availability of information – assesses the implementation of good regulatory practices on transparency, measuring whether there is a dedicated government website or trade information portal explaining international trade procedures and regulations, whether relevant information on international trade is made publicly available in practice and free of charge, whether the government regularly provides advance notification of regulatory changes, and the frequency of consultations between the government and the trading community. (2) Electronic systems and interoperability of services – assesses the availability, scope, connectivity, and functionality of an economy’s electronic platforms for trade operations, measuring which agencies and other trade actors are connected through an electronic single window, what features the platform has, and its bilateral, regional, or multilateral interoperability. (3) Risk management – assesses the availability and features of an integrated risk management system, measuring the level of risk and information sharing, integration, inclusiveness, coordination in a risk assessment matrix, as well as the criteria applied and use of risk-based selectivity. (4) Border agency programs – assesses the availability and characteristics of AO/AEO schemes and other customs and border agency programs which provide benefits for traders, such as Post-Clearance Audits, education and outreach programs for the trading community and expedited shipments. Measuring the criteria, applicability and the benefits of these programs will build on the data collected by the WCO, as customs agencies report key design aspects of their AEO and Customs Compliance programs. (5) Internal/External cooperation – assesses the border and behind-the-border cooperation with partner countries, measuring the international coordination between domestic agencies responsible for border control and those of other countries (i.e., coordinated border management), the participation in bilateral, regional, or multilateral trade agreements, and the areas covered by those agreements, as well as the availability of simplified trade regimes and other special trade arrangements. Measuring the participation in bilateral, regional, or multilateral trade agreements will build on the existing WTO’s Regional Trade Agreements database, which is notification-based, and WBG Global Preferential Trade Agreements Database and Deep Trade Agreements database, which are not exhaustive. 110 de Sá Porto, P. C., Canuto, O., and Morini, C. 2015. “The Impacts of Trade Facilitation Measures on International Trade Flows.” Policy Research Working Paper No. 7367. Washington, DC: World Bank. 34 (6) Trade infrastructure – assesses the availability, quality, and efficiency of essential physical infrastructure for trade, including road and railway transport networks, maritime transportation, seaports, bonded warehouses, and border checkpoints. This component will build on the WBG’s Logistics Performance Index by expanding on specific measures not covered by that index. c. Efficiency of importing goods, exporting goods, and engaging in e-commerce Operational and transaction costs associated with importing and exporting have become increasingly important and are aggravated when facing low levels of trade facilitation. Inefficient customs clearance procedures, inadequate coordination between border agencies, ineffective implementation of border agency programs, limited logistics services, poor trade, and transport infrastructure, among other factors, substantially increase the time and cost associated with complying with export and import requirements. These increased costs of compliance are substantial barriers to trade, which hinder the ability of firms to access international markets.111 Similarly, when engaging in e-commerce, firms may also face additional compliance costs vis-à-vis traditional trade. This set of indicators will cover five components which will serve as a proxy for the efficiency of trade procedures and the overall burden imposed on the private sector when trading internationally. Data for this de facto indicator will be collected via representative firm-level surveys and can be corroborated by administrative data, for example, Time Release Study data. (1) Operationalization of risk management system – assesses the operationalization in practice of an integrated risk management system, including the share of consignments selected for immediate release, the share of consignments selected for document checks, the share of inspected consignments requiring physical examination, the share of consignments selected for post-entry audits, and the share of consignments leading to additional investigations and/or changes in the declarations. (2) Implementation of border agency programs – assesses the implementation in practice of these programs and the benefits effectively received by compliant traders, including share of customs declarations cleared before the arrival of goods, share of consignments cleared under expedited processing, and percentage of consignments qualified for post-clearance audit. (3) Time and cost to comply with export requirements – assesses the time and cost borne by the private sector when directly exporting goods, including those associated with administrative requirements from customs, use of customs brokers services, product inspection agencies and other border control authorities, logistics and freight, and trade finance. (4) Time and cost to comply with import requirements – assesses the time and cost borne by the private sector when directly importing goods, including those associated with administrative requirements from customs, use of customs brokers services, product inspection agencies and other border control authorities, logistics and freight, and trade finance. (5) Time and cost to engage in e-commerce – assesses the time and cost associated with obtaining, registering, and protecting domain names (such as for a digital platform), the time for a merchant to receive online payments into its merchant account (by comparing domestic e-commerce versus cross- border e-commerce), and the cost for purchasing cyber liability insurance. 111 Volpe Martincus, C., Carballo, J., and Graziano, A. 2015. “Customs.” Journal of International Economics, 96 (1): 119–137. 35 G. Taxation 1. Motivation Taxation is a powerful policy tool that governments use to generate revenues to finance their operations and provide public goods and services. Taxation affects the development of the private sector through a variety of inter-related channels. On the one hand, it creates enabling conditions for growth and development of the private sector by financing physical infrastructure, human capital investments, law enforcement and other public services. On the other hand, excessive taxation can distort markets, alter investment decisions, and foster tax evasion.112 Likewise, cumbersome regulations, complex tax reporting requirements, and the need to frequently interact with tax officials pose a considerable compliance cost on private firms113, thus discouraging formalization.114 The identification of key issues faced by taxpayers and critical features of tax systems can help inform reforms that support private sector development while pursuing domestic resource mobilization (DRM) objectives. Academic research highlights four key drivers of tax systems deficiencies that affect economic outcomes, and influence investment decisions: (1) complexity of tax systems115, 116, (2) efficiency of tax administration systems117, (3) tax burden and (4) the cost of compliance with tax regulations.118 BEE indicators therefore include measures to incorporate all these issues. Research shows that tax complexity is a byproduct of designing and reforming a tax system.119 While a universally accepted definition of tax complexity is missing, empirical research specifically points out that the complexity of tax legislation is often associated with information overload, confusion, uncertainty, and taxpayer frustration. 120 Furthermore, complexity and uncertainty, in the sense of multiple tax rates, indeterminate language in the tax law and inconsistent changes in the tax laws, have a significant negative effect on inward FDI.121 On the contrary, clear, simple, and detailed legislation is easier to follow and comply with. Tax certainty reports of IMF and OECD find that clearer and less ambiguous tax regulations support economic growth.122 The efficiency of tax administration systems is another aspect that affects the burden of administrative compliance. Academic research shows that economies with tax administration procedures that provide easy access to information, build e-tax systems, employ effective risk management strategies, and ensure 112 Clotfelter, Charles T. 1983. "Tax Evasion and Tax Rates: An Analysis of Individual Returns." The Review of Economics and Statistics 65 (3): 363-373. 113 Alm, James, Cherry, Todd, Jones, Michael, McKee, Michael. 2010. “Taxpayer Information Assistance Services and Tax Compliance Behavior.” Journal of Economic Psychology 31:577–86. 114 Coolidge, Jacqueline and Ilic, Domagoj. 2009. “Tax Compliance Perceptions and Formalization of Small Businesses in South Africa”. World Bank Policy Research Working Paper No. 4992 115 Slemrod, J. 1989. “Complexity, compliance costs, and tax evasion”. In J. A. Roth & J. T. Scholz (Eds.), Taxpayer compliance (pp. 156–181). University of Pennsylvania Press. 116 Evans, C., & Tran-Nam, B. 2010. “Controlling tax complexity: Rhetoric or reality?” In C. Evans, R. Krever, & P. Mellor (Eds.), Australia’s future tax system: The prospects after Henry (pp. 439–463). Thomsen Reuters. 117 Dabla-Norris, Era, Florian Misch, Duncan Cleary, and Munawer Khwaja. 2017. “Tax Administration and Firm Performance: New Data and Evidence for Emerging Market and Developing Economies”. IMF. 118 Eichfelder, S., & Hechtner, F. 2018. “Tax compliance costs: Cost burden and cost reliability”. Public Finance Review, 46(5), 764–792. 119 Hoppe, Thomas and Schanz, Deborah and Sturm, Susann and Sureth-Sloane, Caren. 2021. “The Tax Complexity Index – A Survey-Based Country Measure of Tax Code and Framework Complexity”. TRR 266 Accounting for Transparency Working Paper Series No. 5, WU International Taxation Research Paper Series No. 2019-06 120 Abeler, J., and S. Jäger. 2015. “Complex tax incentives”. American Economic Journal: Economic Policy 7 (3): 1-28. 121 Kelly Edmiston and Shannon Mudd & Neven Valev. 2003. “Tax Structures and FDI: The Deterrent Effects of Complexity and Uncertainty”. Fiscal Studies, Institute for Fiscal Studies, vol. 24(3), pages 341-359. 122 International Monetary Fund (IMF), & Organisation for Economic Co-operation and Development (OECD). 2019. Progress report on tax certainty. Paris: OECD Publishing. 36 transparency of operations benefit from increased firm productivity and economic growth.123 Other research shows that while investments in e-filing and e-payment tax systems are effective in reducing compliance costs124, corruption125, 126, and tax evasion127, they also have inspired organizational changes and increased the uptake of information technology within firms.128 Likewise, the presence of impartial, accessible, and efficient tax dispute resolution mechanisms is essential for protecting a taxpayer’s right to challenge a tax assessment and get a fair hearing in a timely manner.129 Globalization and the resulting growth in capital mobility has put increasing pressure on governments to engage in tax competition.130, 131 Analysis of various strategies of tax competition points at tax reduction practices as the most popular policy measures to attract multinational investors and discourage domestic capital flight.132 This approach ignores the fact that investors look, not only at the tax burden, but also at other aspects of the tax systems highlighted above such as complexity of tax regulations and efficiency of tax administration. By providing the appropriate regulatory framework and public services, tax administrations can reduce the compliance burden while achieving their DRM goals. 2. Indicators in the area of taxation BEE uses three sets of indicators in the area of taxation: (a) the quality of tax regulations (regulatory framework pillar), (b) the services provided by the tax administration (public services pillar), and (c) the tax burden and efficiency of tax systems (a measurement that reflects the impact of the two previous pillars). Compared to the previous Paying Taxes topic of Doing Business, the BEE indicators cover new issues and have a broader scope. BEE has developed a framework that provides measures for assessing complexity of tax regulations, efficiency of tax systems, tax burden and cost of compliance. The quality of tax regulations and most of the services provided by the tax administration are new areas. The tax burden will be measured by the total tax and contribution rate, which builds on the methodology developed by Doing Business but revises it in line with some recommendations outlined by the External Panel Review to make it representative of economic conditions of individual countries and to incorporate economic incidence of taxes. The efficiency of tax systems will build on the previous Paying Taxes indicator. Additionally, BEE includes an environmental taxation aspect, capturing fiscal tools to discourage or cap activities that are harmful to the environment. This framework will assess these aspects in a manner consistent with internationally recognized best practices in the areas of tax policy and administration. 123 Dabla-Norris, Era, Florian Misch, Duncan Cleary, and Munawer Khwaja. 2017. “Tax Administration and Firm Performance: New Data and Evidence for Emerging Market and Developing Economies”. IMF. 124 Ali, Merima and Shifa, Abdulaziz and Shimeles, Abebe and Woldeyes, Firew B. 2015. “Information Technology and Fiscal Capacity in a Developing Country: Evidence from Ethiopia”. ICTD Working Paper 31. 125 Inasius, Fany. 2015. “Tax Compliance of Small and Medium Enterprises: Evidence from Indonesia”. Accounting & Taxation, v. 7 (1) pp. 67-73. 126 Okunogbe, Oyebola M., Pouliquen,Victor M. J. 2018. “Technology, taxation, and corruption: evidence from the introduction of electronic tax filing”. Policy Research working paper, no. WPS 8452, Impact Evaluation series Washington, D.C.: World Bank Group. 127 Kochanova, A., Hasnain, Z., Larson, B., 2020. “Does E-Government Improve Government Capacity? Evidence from Tax Compliance Costs, Tax Revenue, and Public Procurement Competitiveness”. The World Bank Economic Review, Volume 34, Issue 1, Pages 101–120, 128 Timothy F. Bresnahan, Erik Brynjolfsson, Lorin M. Hitt. 2002. “Information Technology, Workplace Organization, and the Demand for Skilled Labor: Firm-Level Evidence”. The Quarterly Journal of Economics, Volume 117, Issue 1, Pages 339–376 129 Koos, Edward. 2014. “Tax Dispute Resolution Mechanisms in Developed and Developing Countries: An Analysis of Factors that Affect Dispute Mechanism Design and Functionality”. 130 Michael P. Devereux, Alan J. Auerbach, Michael Keen, Paul Oosterhuis, Wolfgang Schön, and John Vella. 2021. “Taxing profit in a global economy”. Oxford University Press 131 Gropp, R., & Kostial, K. 2001. “FDI and Corporate Tax Revenue: Tax Harmonization or Competition?” Finance & Development, 0038(002). 132 Philipp Genschel, Peter Schwarz. 2011. “Tax competition: a literature review”. Socio-Economic Review, Volume 9, Issue 2, Pages 339–370 37 a. Quality of tax regulations While understanding how a country mitigates the negative effects of tax complexity is critical, it is difficult to quantify the level of complexity and ambiguity in tax legislation, and its evaluation on a global scale is bound to be highly subjective. What can be measured more objectively, however, is the following: (1) whether there are systems in place to routinely address complexities and ambiguity in regulations, through issuing clarifications and interpretations through public rulings, private rulings, and tax notes; (2) whether there is long-term stability in tax regulations; (3) whether the requirement for keeping and filing tax records are cumbersome; and (4) whether the process for introducing new tax regulations is transparent. This set of indicators will focus on the following drivers of complexity and mechanisms in place to address them: (1) Addressing clarity of tax provisions – This indicator measures the systems in place for obtaining business feedback through surveys, FAQs on websites, and public contact centers, and providing guidance to businesses by issuing clarifications and interpretations through public and private rulings to provide certainty. The indicator will also look at the availability of specialized guidance on compliance with environmental tax regulations and communications aimed at increasing public awareness and acceptance of green taxes. (2) Stability of tax regulations – This indicator measures how frequently tax provisions are amended over periods of time. It will focus on the core national tax laws and measure the stability of the rate structure of national taxes, frequency of amendments to the corporate income tax law (computation of income, deductions, and exemptions), to the VAT law (taxable transactions, zero rates and exemptions), and to regulations on environmental taxation. (3) Complexity of record keeping and filing– This indicator measures the number of supporting documents that businesses have to store and file on a regular basis. This indicator will focus on: (1) the number of documents that are required by law to be filed with CIT returns, other than the financial accounts that businesses normally maintain (balance sheets, profit, and loss account), and (2) the flexibility allowed in regulations for submitting electronic invoices instead of hard copies for VAT filings. (4) Transparency in the formulation of tax regulations– This indicator measures whether the authorities routinely inform businesses of future changes in procedures and processes and the time between the announcement of tax changes and their enactment. It will also assess whether authorities conduct regulatory impact assessments and public consultation for all new regulations, including environmental taxation. This set of de facto indicators will be measured based on international good practice standards specified by OECD and IMF. Data will be collected through expert consultations (with ministries of finance and tax administration officials, tax practitioners, tax lawyers, tax accountants, and tax experts who are familiar with the support that the tax administrations provide) and corroborated with administrative data from tax authorities. Publication of laws/regulations, jurisprudence (of matter decided cases) and law interpretations will also be taken into consideration. b. Services provided by the tax administration This set of indicators will assess the quality of tax administration in four performance areas, including (1) availability of electronic systems for tax filing, payment, and assessment, (2) use of risk-based selection of cases for tax audit and verification, (3) presence of effective and efficient dispute resolution mechanisms, and (4) transparency of tax administration operations. It will build on the best practices defined by the Tax Administration Diagnostic Assessment Tool (TADAT)133, the Forum on Tax Administration (FTA)134 and the Intra-European Organization of Tax Administrations (IOTA)135. 133 TADAT website: https://www.tadat.org/home 134 https://www.oecd.org/tax/forum-on-tax-administration/ 135 https://www.iota-tax.org/ 38 (1) Electronic systems for tax filing, payment, and assessment – This indicator assesses the quality of the information and communications technology infrastructure of the tax administration, including the availability of online public services provided to taxpayers (e.g., e-filing and e-payment tax systems, taxpayer portals, pre-filled tax returns, and electronic self-service tools). It also looks at the extent of the interoperability between tax administration and other government institutions (e.g., cross- referencing, and automatic exchange of information) that reduces the need to request information from business that is already available otherwise. The proposed methodology will focus on collecting data on electronic services to look at the uptake of such systems (for e-filing and e-payment). (2) Risk-based audit – This indicator assesses the existence, within the tax authority, of an effective risk- based audit selection that will target mainly high-risk categories of taxpayers and not most businesses, where audit cases are selected centrally and not by the audit units, and where there are transparent and effective audit procedures. The assessment will also cover the capacity of tax administrations to gather information from third-party sources (including other government agencies) which will reduce the need for requiring taxpayers to furnish documents that the authorities can obtain directly from third parties. Best practices provided by OECD and IMF will be used as a way for categorization. (3) Dispute resolution mechanisms – This indicator assesses the timeliness and quality of procedures and institutions established by the tax administration to resolve tax disputes. It will focus on evaluating the structure and independence of the dispute resolution mechanisms by looking at whether the tax authority has simple, transparent, and independent dispute resolution mechanisms, (i.e., reviews are undertaken by designated review officers independent of the audit department); followed by appeal to an independent external specialist tax tribunal, or court in case the taxpayer is dissatisfied with the outcome of an administrative review (an alternative fast-track dispute resolution process involving arbitration may also be in place).136 It will also measure the time taken to dispose of administrative reviews. Tax administration statistics will be used as primary data for timeliness of resolution of disputes, to the extent that they are available and reliable. The IMF and OECD guidelines will be used to measure the level of independence of the administrative review process and the speed with which disputes are resolved. (4) Transparency of tax administration – This indicator assesses the extent to which the tax administration is transparent in reporting its activities and future strategies that affect businesses. It will focus on publication of annual reports on financial and operational performance and future strategies and plans; staff integrity assurance mechanisms; and strong external oversight of the tax administration. The proposed methodology will focus on the reports published by tax administrations and all relevant public information. The IMF-TADAT guidelines will be used to measure the level of transparency of tax administration. Data for this de facto set of indicators will be collected through expert consultations and can be corroborated through administrative data from tax authorities. c. Tax burden and efficiency of tax systems This set of indicators will evaluate how efficiently tax regulation and public services are implemented in practice from the perspective of the firm. More specifically, by relying on the experience of firms and expertise of local tax professionals, the indicators will measure the burden of taxes imposed on private businesses as measured by the total tax and contribution rate, and efficiency of services provided by tax administration measured in terms of time to comply with tax regulations. This set will have two indicators: (1) total tax and contribution rate (TTCR), and (2) time to comply with tax regulations. 136 IMF, “TADAT Filed guide”, 2019. https://www.tadat.org/assets/files/TADAT%20Field%20Guide%202019%20-%20English.pdf 39 (1) Total tax and contribution rate – This indicator measures the tax burden borne by businesses from paying three core taxes: profit taxes, consumption taxes, and social taxes and contributions. While the data on the statutory tax rates for various types of taxes are already publicly available, such information cannot be used as a tax burden measure, because statutory rates tell an incomplete story. Firms typically pay lower effective tax rates than the nominal rates as a result of tax incentives, deductions, and reliefs. The indicator will address these limitations in the data and offer a precise measure of the tax burden by collecting information on effective tax rates. BEE will consider using a hybrid data collection approach, combining firm-level surveys and expert consultations. The hybrid approach will include a two-stage data collection process. In the first stage the key characteristics of the case study company will be formulated. The representative firm-level data will be used to define the total turnover, number of employees, and asset structure, economic sector, and size. To allow comparability of the data across sectors, several case study companies will be developed to represent 2-3 dominant sectors in an economy. Further, to allow capturing differences between larger and smaller firms, the size of the case study companies will be defined based on the top decile, and median firms as reported by the firm level surveys. By utilizing the hybrid approach, BEE will incorporate individual economy characteristics (sector composition, size of private firms) into the analysis. Since sectoral composition and sizes of firms do not change often over time, the main characteristics of the case study company will be updated once in 3-4 years. The relevance and feasibility of this approach for designing case study companies will be tested during the piloting stage. In the second stage – the main data collection process - the data for the total tax and contribution rate will be collected through expert consultations with tax lawyers, tax accountants, and tax experts who are familiar with the regulations and changes in taxation related to businesses. Under the Doing Business methodology the TTCR focused on computing the burden of taxes levied on businesses. BEE will change this approach in line with some recommendations outlined by the External Panel Review and will focus on “taxes collected and remitted by businesses, including both those levied on businesses and those levied on workers and purchasers (e.g., VAT) but collected and remitted on their behalf by businesses”.137 This approach for the scope of taxes that are considered for TTCR is based on the fact that determining economic incidence of various taxes is not feasible since this would require data on price elasticity which is available only for a handful of countries. Therefore, for measuring consumption tax such as VAT in the TTCR, BEE will use the net tax actually paid by the business (i.e., after deducting input credit). For social taxes and contributions, as a proxy for economic incidence, BEE will include 50 percent of the total social taxes and contributions paid cumulatively by the employer and the employee. International experience shows that many countries follow the practice of charging equal employer-employee contribution for social and pension funds.138 This approach will likely diminish the adverse incentive of countries to shift the statutory incidence of social taxes to employees even though this does not change the economic burden. BEE will test the relevance of this approach during the piloting stage. (2) Time to comply with tax regulations – This indicator assesses three dimensions of administrative compliance with tax regulations: (1) time to file and pay mandatory taxes, including the time to prepare, file and pay profit taxes and VAT/sales taxes, (2) time to complete and obtain a VAT refund, and (3) duration and frequency of tax audits. In relation to environmental taxation, the number of environmental taxes and associated cost of compliance with them will be assessed. In addition, an attempt will be 137 Doing Business: External Panel Review, Final Report. 2021. 138 Example of countries using equal employer-employee contributions include Germany, the Netherlands, Luxembourg, Malta, Poland, Switzerland and Cyprus. Source of the data: EU’s Mutual Information System on Social Protection, accessed at https://www.missoc.org/missoc-database/. 40 made to assess the impact of environmentally damaging practices of informal firms on operations of formal firms as perceived by survey respondents. BEE will collect data for the time to comply with tax regulations, a de facto indicator, through firm- level surveys to ensure representativeness. 41 H. Dispute resolution 1. Motivation In both developed and developing economic systems, commercial disputes inevitably occur. When these disputes cannot be resolved properly, adverse economic outcomes might arise for the private sector.139 This makes a well-functioning judicial system a key part of a healthy business environment. Such a judicial system requires efficiency and quality. First, time- and cost-effective mechanisms for resolving disputes are indispensable for private sector development. Excessively long and expensive proceedings may defeat the very purpose of litigation, making it unattractive and inaccessible. In the literature, a strong correlation has been established between judicial efficiency and facilitated entrepreneurial activity.140 Slow court systems are associated with smaller firms and costlier bank financing.141 Evidence also suggests that under a more effective court system businesses tend to have greater access to finance and borrow more.142 It equally finds that firms operating in areas with less congested civil courts experience a larger increase in the use of secured loans.143 Fast judiciaries are also associated with higher levels of domestic and foreign investment.144 Whenever investors know that in case of non-performance of an obligation their claim will be considered in a timely manner, they have more incentives to deploy additional capital. 145 Further, enhancing the efficiency of the judiciary can strengthen competition and foster innovation.146 Second, quality of the dispute resolution process matters too for private sector development. Claims should be considered with due care and by credible institutions. Well-reasoned judgment should be issued at the end of a trial. Research has shown that in countries where there is little confidence in the court system, firms are less willing to expand their businesses and look for alternative trade partners. 147 To attract investors, economies need to ensure that their judiciaries are not only fast, but also strong and reliable.148 Limited enforceability of contracts leads to suboptimal distribution of resources, delayed arrival of new technologies, and greater macroeconomic volatility.149 Finally, because inadequate commercial dispute 139 Esposito, Gianluca, Sergi Lanau, and Sebastiaan Pompe. 2014. “Judicial System Reform in Italy – A Key to Growth.” IMF Working Paper WP/14/32, IMF, Washington, DC. 140 Ippoliti, Roberto, Alessandro Melcarne, and Giovanni B. Ramello. 2015. “Judicial Efficiency and Entrepreneurs’ Expectations on the Reliability of European Legal Systems.” European Journal of Law and Economics 40 (1): 75–94. 141 Fabbri, Daniela. 2010. “Law Enforcement and Firm Financing: Theory and Evidence.” Journal of the European Economic Association 8 (4): 776–816. 142 Moro, Andrea, Daniela Maresch, and Annalisa Ferrando. 2018. “Creditor Protection, Judicial Enforcement and Credit Access.” The European Journal of Finance 24 (3): 250–281. 143 Ponticelli, Jacopo, and Leonardo S. Alencar. 2016. “Court Enforcement, Bank Loans, and Firm Investment: Evidence from a Bankruptcy Reform in Brazil.” The Quarterly Journal of Economics 131 (3): 1365–1413. 144 Koutroumpis, Pantelis, and Farshad R. Ravasan. 2020. “Do Court Delays Distort Capital Formation?” Working Paper No. 2020-4, Oxford Martin Working Paper Series on Economic and Technological Change, University of Oxford, Oxford. 145 Chemin, Matthieu. 2009. “The Impact of the Judiciary on Entrepreneurship: Evaluation of Pakistan’s “Access to Justice Programme”.” Journal of Public Economics 93 (1-2): 114–125. 146 OECD (Organisation for Economic Co-operation and Development). 2013. “What Makes Civil Justice Effective?” OECD Economics Department Policy Notes No. 18, OECD, Paris. 147 World Bank. 2004. World Development Report 2005: A Better Investment Climate for Everyone. Washington, DC: World Bank. 148 World Bank. 2019. Moldova: Rekindling Economic Dynamism. Country Economic Memorandum. Washington, DC: World Bank. 149 Cooley, Thomas, Ramon Marimon, and Vincenzo Quadrini. 2004. “Aggregate Consequences of Limited Contract Enforceability.” Journal of Political Economy 112 (4): 817–847. 42 resolution might deprive firms of timely and full payments, liquidity and insolvency issues can arise, and so can subsequent bankruptcies and unemployment.150 Efficiency and quality of commercial dispute resolution rely on adequate public services. A great deal of disputes between private firms eventually necessitates court involvement, thereby underscoring the importance of establishing a robust institutional framework.151 Recent research has emphasized that not only solid de jure rules but also strong de facto judicial institutions are required for economic growth.152 As demonstrated by the pandemic, one essential feature that can help create better institutions in the current context is their digitalization.153 Introducing relevant e-services thus carries a promise of making the dispute resolution process more efficient and fairer, to benefit the private sector.154 2. Indicators in the area of dispute resolution BEE uses three sets of indicators in the area of dispute resolution: (a) the quality of regulations for commercial dispute resolution (regulatory pillar); (b) the adequacy of public services in commercial litigation (public services pillar); and (c) the ease of resolving a commercial dispute (reflecting how the two pillars pertaining to the quality of regulations and adequacy of public services contribute in practice to effective and fair resolution of disputes). These sets of indicators will focus on the resolution of commercial disputes – disputes that arise in the business context between private firms. Limited aspects of dispute resolution between a private party, on the one hand, and a public agency or state-owned enterprise, on the other hand, will also be measured. Throughout the topic, commercial disputes are not meant to include more specific types of litigation, such as corporate lawsuits or intellectual property cases. That said, certain parameters measured by the indicators (for example, quality of regulations, specialization of courts, digitization, etc.) may also incidentally benefit other areas of dispute resolution. In contrast to the Enforcing Contracts topic of Doing Business, the BEE project will assess the efficiency and quality of commercial dispute resolution, without focusing on individual SMEs or on a specific case study scenario. Furthermore, the new sets of indicators will also incorporate international aspects of resolving disputes and cover both domestic and foreign enterprises. Other important additions, explained in more detail below, will include a larger focus on public services and collecting data on the ease of commercial dispute resolution directly from firms. a. Quality of regulations for commercial dispute resolution This set of indicators will focus on the quality of legislation that pertains to both in-court processes and alternative dispute resolution (ADR) mechanisms to serve as a reliable proxy for the topic in question. This is primarily a de jure set of indicators that will look at provisions that promote efficiency and quality alike. Specifically, it will determine whether domestic laws follow a set of internationally recognized good regulatory practices intended to make resolving disputes effective and fair. In addition, when relevant legal 150 Esposito, Gianluca, Sergi Lanau, and Sebastiaan Pompe. 2014. “Judicial System Reform in Italy – A Key to Growth.” IMF Working Paper WP/14/32, IMF, Washington, DC. 151 See, e.g., Peev, Evgeni. 2015. “Institutions, Economic Liberalization and Firm Growth: Evidence from European Transition Economies.” European Journal of Law and Economics 40 (1): 149–174. 152 Marciano, Alain, Alessandro Melcarne, and Giovanni Ramello. 2019. “The Economic Importance of Judicial Institutions, Their Performance and the Proper Way to Measure Them.” Journal of Institutional Economics 15 (1): 81–98. 153 Susskind, Richard. 2020. “The Future of Courts.” The Practice (Harvard Law School) 6 (5). https://thepractice.law.harvard.edu/article/the-future-of-courts/. 154 Cabral, James E., Abhijeet Chavan, Thomas M. Clarke, John Greacen, Bonnie Rose Hough, Linda Rexer, Jane Ribadeneyra, and Richard Zorza. 2012. “Using Technology to Enhance Access to Justice.” Harvard Journal of Law & Technology 26 (1): 241– 324. 43 provisions are in place, the set of indicators will also assess if these are respected in practice. Measuring both rules on the books as well as actual compliance with them is crucial because, as evidenced by research, private sector growth requires both.155 The discussed good practices in the fields of in-court litigation and alternative dispute resolution derive from authoritative projects and institutions. To name a few, in the WBG many such practices were incorporated within the Justice Needs and Institutional Performance Review (JUNIPER) framework and the World Bank Good Practices for Courts report. Other internationally recognized instruments include the Council of Europe CEPEJ Checklist for Promoting the Quality of Justice and Courts, UNCITRAL Model Law on International Commercial Arbitration, UNCITRAL Model Law on International Commercial Conciliation, New York Convention on the Recognition and Enforcement of Arbitral Awards, and others. As it is not practical to cover all the good practices from the named sources, the BEE project will focus on the most relevant ones based on the private sector needs in the area of resolving disputes in the post- pandemic world. The data for the quality of regulations indicators will be collected through expert consultations. This is because local practitioners – lawyers in commercial litigation – possess the best knowledge of relevant laws and their application in practice. The process of expert consultations will be corroborated by desk research. The quality of regulations for commercial dispute resolution will have two indicators. (1) In-court litigation processes – The first indicator will focus on the quality of regulations applicable to in-court litigation processes. Provisions related to both efficiency and quality will be targeted. For example, this indicator will measure whether commercial (or civil, where applicable) procedure legislation establishes timeframes for different stages of commercial litigation and whether the judge and litigants can be held accountable for not respecting them. In this vein, it will equally examine whether the regulations provide for holding a pre-trial conference – a practice aimed at clarifying the scope of a dispute from the very beginning. Aspects of enforcement of judgments will be covered as well, with an assessment of whether there are time standards within which judgments should be executed and what types of assets can be seized by an enforcement agent. (2) Alternative dispute resolution mechanisms – The second indicator will measure the quality of regulations governing alternative dispute resolution mechanisms (arbitration and mediation). When supported by a strong legal framework, these mechanisms can be used by private parties to resolve their disputes more efficiently and flexibly. Well-functioning ADR mechanisms can help reduce court backlogs and improve the quality of resolving disputes by sharing knowledge and expertise.156 The arbitration section of the component will largely draw on the previous studies of the WBG in this area: Investing across Borders (2010), and Arbitrating and Mediating Disputes (2013). In terms of regulations that support efficiency, this set of indicators will measure procedural timeframes and confirmation, recognition and enforcement of arbitral awards. As to provisions that promote quality of the arbitration process, the section will look into the form of the arbitration agreement, arbitrability of commercial disputes, parties’ autonomy, and judicial support of arbitration, including ruling on the validity of arbitration clauses or agreements, and general assistance to the arbitration proceedings. In addition, some other areas relevant to arbitration will be considered for inclusion in the next phases of 155 Ndungu, Joseph, and Peter Muriu. 2017. “Do Good Institutions Matter for Private Investment? Evidence from East Africa.” Journal of Economics and Sustainable Development 8 (6): 18–29. 156 World Bank. 2011. Alternative Dispute Resolution Center Manual: A Guide for Practitioners on Establishing and Managing ADR Centers. Washington, DC: World Bank. 44 the project. These are arbitrators’ independence and impartiality, proceedings against public entities, expedited proceedings, multi-party proceedings, and others. With regards to mediation and conciliation services (including court-annexed ones), the indicator will measure requisites to attempt mediation or conciliation, existence of financial incentives to engage in these, as well as the enforcement regime for settlement agreements. b. Adequacy of public services in commercial litigation The set of indicators will assess the adequacy of public services provided to resolve a commercial dispute. Even when an economy has crafted a robust legal framework, its practical application can vary dramatically depending on the existing institutional arrangements, and information and communications technology (ICT) infrastructure. More specifically, the effectiveness and fairness of dispute resolution can be impacted by the expertise and independence of judges, courts’ transparency, and availability of e-services, among other factors. This is a de facto set of indicators that will focus on the actual availability and quality of public services beyond the legal framework. The data will be collected through expert consultations. As is the case with quality of regulations, lawyers in commercial litigation have the best knowledge of institutional arrangements and ICT infrastructure since they deal with them on a daily basis. Furthermore, data collection through expert consultations is more informative than firm-level surveys because most businesses go to courts only occasionally and, when they do, they tend to rely on lawyers to resolve disputes – whether hired attorneys or in-house ones. Private firms may therefore have only superficial knowledge of specific features of the services provided. For these reasons, and particularly in the area of court automation and e-services, the data will reflect the experience of regular users, although various aspects of these services are equally relevant to occasional litigants. The adequacy of public services in commercial litigation will have two indicators. (1) Institutional framework – Academics generally agree that the quality of institutions plays a key role in how disputes are resolved.157 For example, commercial dispute resolution can be impacted by such institutional arrangements as specialization of judges, extent of formalism and independence of the judiciary. 158 This indicator will capture those aspects by looking at the existence of specialized courts/chambers at both first instance and appeal levels, presence of small claim courts and types of services provided by ADR centers. Furthermore, judicial expertise, independence, impartiality, and transparency will be equally measured. The indicator will thus study whether the latest versions of the laws are made publicly available free of charge, whether commercial judgments get published in open sources, whether these judgments are well-reasoned, and so on. (2) Court automation and e-services – The second indicator will focus on digitalization of commercial litigation across different levels of the judiciary. ICT infrastructure in dispute resolution is still a relatively new area; however, the COVID-19 pandemic has demonstrated its importance for effective and inclusive resolution of disputes. Overall, digital solutions have the potential to (i) improve efficiency in case management by expediting processing time; (ii) provide better access to justice through online tools; and (iii) increase transparency by facilitating access to information.159 157 Marciano, Alain, Alessandro Melcarne, and Giovanni Ramello. 2019. “The Economic Importance of Judicial Institutions, Their Performance and the Proper Way to Measure Them.” Journal of Institutional Economics 15 (1): 81–98. 158 See, e.g., Melcarne, Alessandro, and Giovanni Ramello. 2015. “Judicial Independence, Judges’ Incentives and Efficiency.” Review of Law & Economics 11 (2): 149–169. 159 Cordella, Antonio, and Francesco Contini. 2020. Digital Technologies for Better Justice: A Toolkit for Action. Washington, DC: IADB (Inter-American Development Bank). 45 For example, this indicator will examine the functioning of E-Systems that allow for electronic filing of cases, exchange of procedural documents and notifications between courts and their users and holding virtual hearings. In addition, acknowledging the increasing importance of artificial intelligence (AI) and machine learning (ML) for better judicial decision-making, the indicator will also study the potential inclusion of these areas in the next phases of the project. c. Ease of resolving a commercial dispute A key contribution of this set of indicators will consist in determining how reliable, accessible and efficient court mechanisms are in general (i.e., whether cases are worth pursuing in the first place and why if not), as well as in providing specific details on time and cost for different parts of litigation (i.e., what time and cost to expect). The ease of resolving a commercial dispute is a de facto set of indicators. As mentioned above, unlike Enforcing Contracts of Doing Business it will collect information from both firms and experts to measure the efficiency and credibility of the dispute resolution system. It will consist of three indicators. (1) Obstacles to justice – The first indicator will identify the main perceived obstacles for bringing commercial disputes to court. Firms that have faced a commercial dispute within a defined timeframe will be asked to share their experience and identify major obstacles for efficient and fair resolution of disputes. These can include lack of trust in the fairness of the judicial process, insufficient expertise of judges, excessive duration of proceedings, manifestly high cost of litigation, and others. The indicator will distinguish between two types of firms (domestic and foreign) as well as two types of disputes: those among two private firms (whether domestic or foreign), and those against a public agency (e.g., tax authority or another representative public sector agency). The data for this indicator can be best collected through firm-level surveys, using Enterprise Survey methods. First, businesses are the ultimate beneficiaries of the justice system and therefore it is particularly important to know their actual experience. Second, firms often decide whether it is worth going to court before hiring a lawyer, so experts may have insufficient knowledge about the firm’s decision process. Firms operating in all sectors can respond and provide original insights on the quality of the justice system. To ensure the accuracy of the data, however, firms that have not had relevant experience will be excluded from the sample. No specific case study is needed to collect these data, besides a clarification that firms should refer to commercial disputes relating to the conduct of their business that occurred within a specified timeframe (for example, the past 5 years). (2) & (3) Time and cost to resolve a commercial dispute – The second and third indicators will be dedicated to the time and cost needed to resolve a commercial dispute, providing specific estimates for different parts of litigation when a firm decides to go to court. The time indicator will measure the time required for three main stages. 1) Trial at the court of first instance, including filing of a case, serving the complaint on the defendant, submitting a request for interim measures, preparing an expert testimony and delivering a judgment. 2) Trial at the appeal stage, which includes filing of an appeal, its review and issuance of a final ruling. 3) Enforcement of a judgment that will cover obtaining a copy of the final ruling, seizing the property and its sale through a public auction. The cost indicator will assess expenses and fees generally incurred in commercial litigation by a good faith party: attorney fees, court fees, expert fees, and enforcement fees, as well as whether any of them can be recovered from the losing party. The data for the second and third indicators can be best collected through expert consultations. This is because local experts in litigation handle cases on a regular basis (whereas litigation can be a relatively rare 46 event for firms), closely monitor changes in this area, and possess technical knowledge of various elements of the litigation process (e.g., appeal trial time, enforcement costs). Thus, they are better equipped to identify bottlenecks and inefficiencies in court practice. To collect the data on time and cost, a simple case study will be used in order to guide respondents and ensure comparability of data. Such a case study will only indicate the name of the city, specify the nature of the dispute, and set an approximate claim value. No assumptions pertaining to the size of the firms, their ownership, and sector of operation are necessary. 47 I. Market competition 1. Motivation There is general consensus among academics that effective market competition spurs economic growth by increasing industry and firm productivity, leading to higher gross domestic product, more jobs and higher labor productivity.160 Affecting market entry and exit, unfettered competition stimulates product innovation and service quality, protects consumers and forces market operators to provide their products and services at cost.161 But competition is rarely perfect. Markets fail either due to firms’ behaviors or government interventions. Market power -the firms’ ability to raise price substantially above cost or to offer low quality- must be kept in check.162 Governments have a wide range of tools to deter anti-competitive behaviors, promote market entry, ensure a fair level of competition and reduce distortions created by market failures.163 Competition policy is the set of policies and laws that ensure that competition in the marketplace is not restricted in such a way as to reduce economic welfare.164 Crucial for the business environment and for the economy, competition policy can help alleviate poverty and bring about shared prosperity. In certain major markets where governments are the sole or principal buyer (e.g., education, health, and infrastructure), market entry and firm behavior are directly influenced by the design and implementation of government regulations.165 This topic will benchmark key regulations that promote competitive behaviors from the perspective of the whole private sector, rather than considering their impact on an individual firm. It will assess regulations that deter anticompetitive behaviors of firms, regulations that promote competitive behaviors in government markets, key public services provided to implement such regulations, as well as their efficient implementation. 2. Indicators in the area of Market Competition BEE uses three sets of indicators in the area of market competition: (a) the quality of regulations that promote market competition (regulatory pillar), (b) the adequacy of public services promoting competition (public services pillar), and (c) the efficiency in the implementation of key services promoting market competition (reflecting how the two pillars pertaining to the quality of regulations and adequacy of public services contribute in practice to the promotion of market competition). Each set of indicators will cover aspects of enforcement of competition policy and regulations that focus on improving competition in the private sector, including in markets where the government is a purchaser of services or goods. None of these areas were previously covered by the Doing Business project. a. Quality of regulations that promote market competition The following two de jure indicators will benchmark: (1) the quality of the competition regulations, and (2) the quality of regulations for bidding for public contracts. The data will be collected through expert consultations. Corporate lawyers with expertise in competition will be best suited to answer questions relating to the first indicator; WBG public procurement experts will be best suited to answer questions relating to the second indicator. The process of expert consultations will be corroborated by desk research. 160 World Bank. 2017. A Step Ahead: Competition Policy for Shared Prosperity and Inclusive Growth. Washington, DC. 161 Begazo Gomez,Tania Priscilla. Nyman,Sara. 2016. Competition and poverty. Washington, D.C. : World Bank Group. 162 Tirole, Jean. 2015. “Market Failures and Public Policy”. American Economic Review, 105 (6): 1665-82. 163 Tirole, Jean. 2017. Economics for the Common Good. Princeton University Press. 164 Motta, Massimo. 2004. Competition policy: theory and practice. Cambridge University Press. 165 Worldwide, public procurement accounts for between 10% and 25% of GDP on average. European Commission, DG Enterprise and Industry. 2014. Evaluation of SMEs’ access to public procurement markets in the EU: final report. 48 (1) Quality of competition regulations – This indicator will provide a proxy on the overall quality of competition enforcement by focusing on some aspects of the enforcement of antitrust laws (e.g., anticompetitive agreements, as well as merger control).166 Not all areas of competition policy will be covered in this indicator. For example, some areas are excluded because they are mostly sector-specific (e.g., measures enabling contestability of formerly government regulated monopolies). This indicator will assess economywide regulations that impact the market dynamics of the private sector. No case study will be used for this indicator. This indicator will cover regulations relating to collusion/anticartel enforcement on the one hand, and merger control on the other hand. More specifically, it will measure whether regulations clearly identify anticompetitive practices, empower authorities to investigate and provide for a range of sanctions; the availability of leniency programs that provide incentives to firms to break cartels (e.g., through procedural guarantees, confidentiality, whistleblower protection); the clarity and coverage of merger control regulations, including the types of transactions that do not need to be reviewed (e.g., transactions that fall below notification thresholds or are subject to simplified merger control procedures); the level and type of filing fees for merger review; and the procedural guarantees in antitrust investigations and of the merger review process allowing parties to exercise their rights of defense. Some aspects of consumer protection can also be included as long as they complement competition enforcement. The selection of good practices will be influenced by the Markets and Competition Policy Assessment Toolkit of the Markets, Competition and Technology unit of the WBG. (2) Quality of regulations for bidding for public contracts – A robust regulatory framework is crucial for firms to participate in markets where the government is a purchaser. The quality of regulations for bidding for public contracts indicator assesses (de jure) whether public procurement regulatory frameworks provide a fair assessment process, legal certainty for firms and include selected internationally recognized good practices that promote competition, transparency, integrity, and best value for money. The scope will be limited to assessing regulations that promote market entry and competitive behaviors to benefit the whole private sector.167 Additionally, this indicator will measure good regulatory practices integrating environmental/sustainability considerations in public procurement, focusing in areas that benefit market entry and competition. The selection of good practices will be consistent with the Methodology for Assessing Procurement Systems.168 Procurement rules and practices might differ across sectors. In order to identify if good regulatory practices have been widely adopted, this indicator would collect data as applied to the three largest purchasers of the federal/central government (to be determined via expert consultations).169 Goods and services subject to specific safety or national security regulations will be excluded from consideration. b. Adequacy of public services that promote market competition This set of indicators will benchmark public service delivery that promote market competition through: (1) the institutional framework and quality of enforcement of competition regulations, and (2) e-procurement. (1) Institutional framework and quality of enforcement of competition regulations – Having a competition authority is key to effectively enforce competition regulations and signal a level playing field in the 166 World Bank. 2017. A Step Ahead: Competition Policy for Shared Prosperity and Inclusive Growth. Washington, DC. 167 For an example of research on best value for money criteria in procurement see Lewis, G. and Bajari, P. 2011. “Procurement Contracting with Time Incentives: Theory and Evidence.” The Quarterly Journal of Economics. 126 (3): 1173-1211, 168 https://www.mapsinitiative.org/ 169Questionnaires would be distributed to WBG procurement experts. 49 market. 170 Competition authorities must operate within a clear and independent framework to investigate firms' behaviors and implement sanctions to deter anticompetitive practices.171 By focusing on the institutional framework and the quality of the enforcement of competition regulations, the indicator will serve therefore as a proxy for the de facto operationalization of competition authorities. Data will be collected through expert consultations (legal practitioners of competition law and representatives of the central competition authority, if applicable) and can be corroborated through desk research. This indicator will capture the institutional framework of the competition authority as implemented in practice, including the extent of its independence (e.g., whether it is exempt from direct supervision by the government), the scope of its mandate (e.g., whether its sole task is to safeguard competition or whether it has more competences assigned), the possibility to appeal its decisions (e.g., whether firms can appeal a decision to a specialized independent body or whether non-judicial bodies can overturn the authority’s decisions), the level of its resources (e.g., budget and staffing), the cooperation with other government agencies (e.g., regulators), and the collaboration with cross-border competition authorities. In addition, this indicator will benchmark the accessibility and transparency of the implementation of competition regulations by measuring whether the competition authority publishes its decisions and the legal and economic justification behind them; issues guidance/advocacy reports on instruments on antitrust and merger control; and enforces sanctions. (2) Transparency and transactional features in electronic procurement platforms – The second de facto indicator assesses e-procurement as a proxy for a government’s actions to promote market entry and reduce anticompetitive behaviors. E-procurement matters because it has the potential to save time, create efficiency and help new firms access the market. E-procurement also facilitates sustainable practices in public procurement through features such as environmental labels, for example. The availability of information promotes equal access for all types of businesses, including small and medium enterprises, by reducing the possibility of large or well-connected firms gaining an advantage because of information asymmetries, and potentially increases competition for government contracts.172 Research suggests that e-procurement facilitates entry by higher quality contractors.173 The indicator is divided into two components: transparency features of e-procurement system, and transactional features. Data – as applied to the three largest purchasers to verify that e-procurement has been widely implemented – will be collected through expert consultations, including with WBG procurement experts and public sector entities. Data can be corroborated through desk research. c. Efficiency in the implementation of key services promoting market competition This set of indicators will assess the efficiency in delivering public services implemented by competition authorities and procuring entities that have an impact on a firm’s decision to enter or operate in the market. Competition authorities enforce competition rules to deter anticompetitive behaviors, while procuring 170 Sergio Mariotti, Riccardo Marzano. 2021. “The effects of competition policy, regulatory quality and trust on inward FDI in host countries”. International Business Review. 30 (6). 171 Jens Høj. 2007. “Competition Law and Policy Indicators for the OECD countries”. OECD Economics Department Working Papers 568. 13 Beschel,Robert P.;Cameron,Blair James;Kunicova, Jana;Myers,C. Bernard. Improving Public Sector Performance: Through Innovation and Inter-Agency Coordination. 2018. Vol. 1 of 2Washington, D.C.: World Bank Group. 173 Lewis-Faupel S, Neggers Y, Olken BA, Pande R. “Can Electronic Procurement Improve Infrastructure Provision? Evidence from Public Works in India and Indonesia”. 2016. American Economic Journal: Economic Policy. 8 (3): 258-283. 50 entities design markets to purchase goods services or works. By focusing on key administrative procedures, it examines how efficient implementation of regulations can support market competition and firm growth. In addition, it will provide quantitative data on competitive behaviors through a survey of a representative sample of firms. There will be four de facto indicators. On administrative procedures, the indicator will benchmark (1) the effective implementation of merger review for a transaction that would typically follow a simplified merger notification procedure, (2) the time to award a public contract through a bidding process, and (3) the time to pay government contractors. To assess the overall effectiveness of competition policy, the indicator will capture (4) some aspects of market dynamism and competitive behaviors as reported by firms, and their knowledge of competition policy regulations. (1) Effective implementation of the simplified merger review – assesses whether the information request process is burdensome for businesses, the time to file a merger notification, to review it and to obtain a decision, and whether competition authorities actually use the simplified procedure appropriately. Inadequate merger review processes, and ineffective implementation of the competition policy can have an overall negative effect on the economy, for example by holding up mergers that do not raise concerns.174 Poorly implemented review processes can also undermine firm growth by discouraging firms to merge if the cost to do so is deemed too high, or if the outcome of the merger review is deemed too uncertain. Most economies have regulations to review merger notifications, and provide simplified procedures, but effective implementation of those is crucial for the business environment. (2) Time to award a public contract – assesses the time between bid opening and public notice of award. In procurement markets, lengthy processes to award contracts and to pay contractors can deter market entry and encourage collusive behaviors. Firms might incorporate the cost to prepare bids and the length of the tender procedure before deciding to participate in the government markets. (3) Time to pay government contractors – assesses the time taken by the government to pay its contractors Late payments create a number of negative externalities on firms, such as disruption of market activity and postponed payment of employees and suppliers. This can have the effect of draining firms' liquidity, and in the presence of limited access to credit, delayed payments can ultimately force firms to exit the market, with additional negative effects on their suppliers and customers.175 (4) Market dynamism and competitive behaviors – provides an overall measure of competition in the markets. Given of the complexity of measuring market concentration, this indicator will assess market dynamics and competitive behaviors through proxy questions addressed directly to businesses about certain characteristics of their markets (for example, market exit rates), and their ability to compete horizontally and vertically without restraints from anticompetitive practices or government regulations (for instance, constraints in their ability to set prices or the ease of changing a utility provider). The data on the implementation of a simplified merger control procedure and on the time to award a contract could be collected via expert questionnaires collected from competition law and public procurement practitioners, respectively. Mergers and acquisitions should be considered a rare event in the life cycle of a firm, therefore lawyers routinely dealing with these issues are better suited to address these questions than the firms themselves. As for time to award a contract, since only a subgroup of firms participates in public tenders, there is a risk that firm-level surveys of a representative sample of an economy’s private sector will not capture enough observations of this subset of companies, thus a targeted approach via questionnaires to 174 OECD. Merger control in the time of COVID-19. 2020. 175 Conti, Maurizio, Elia, Leandro, Ferrara, Antonella Rita, Ferraresi, Massimiliano. ”Late Payments and Firms' Survival: Evidence from the European Union”. 2021. The Journal of Law and Economics. 64 (3): 603-627 51 public procurement experts would be preferred. Several scenarios with some assumptions could be considered (e.g., transaction object of the merger for the effective implementation of merger review, open tendering, restricted tendering, auctions for time to award a contract, to name a few). For the time to pay government contractors and the measures of market dynamism and competitive behaviors, firm-level surveys will be considered. 52 J. Business insolvency 1. Motivation An efficient insolvency framework ensures that non-viable firms are quickly liquidated while viable firms are effectively restructured in a sustainable way. The unsuitability of many insolvency regimes to handle restructuring and liquidation of companies in a timely and effective manner amplifies their level of economic distress. 176 In countries with higher creditor recovery rates and shorter resolution times, restructuring within the formal bankruptcy process tends to fulfil its cyclical role during economic downturns by keeping companies afloat.177 Research shows that efficient insolvency systems enhance new firm creation, increase the size of the private sector, and encourage greater entrepreneurial activity.178 They can boost job creation and growth, including by spurring productivity-enhancing capital reallocation through the exit of non-viable firms.179 Insolvency regimes that encourage corporate restructuring minimize zombie lending, that is lending to otherwise insolvent firms, which slows economic growth through the misallocation of credit and the suppression of competitive forces.180 Countries with less efficient bankruptcy procedures tend to have lower aggregate productivity because their bankruptcy procedures induce lenders to allocate funds to less productive firms.181 Despite the crucial role played by efficient insolvency regimes, large-scale and updated comparable data is scarce. The only data available (for the years 2010 and 2016) is produced by the OECD for 37 high-income countries and with limited substantive scope. The BEE indicators aim at filling this void, while expanding 176 Becker B., and Oehmke M. 2021. “Preparing for the post-pandemic rise in corporate insolvencies.” ASC Insight 2; Greenwood R., Iverson B., and Thesmar D. 2020. “Sizing Up Corporate Restructuring in the COVID crisis.” Brookings Papers on Economic Activity; Ellias J., Iverson B., and Roe M. 2020. “Estimating the need of additional bankruptcy judges in light of the COVID-19 pandemic.” Harvard Business Law Review. 177 Menezes A. 2014. “Debt resolution and business exit: insolvency reform for credit, entrepreneurship, and growth.” World Bank Group Knowledge Note; Consolo A., Malfa F., and Pierluigi B. 2018. “Insolvency frameworks and private debt: an empirical investigation.” Working Paper Series 2189, European Central Bank; Becker B. and Ivashina V. (2021). “Corporate Insolvency Rules and Zombie Lending.” Mimeo. 178 Cirmizi E., Klapper L., and Uttamchandani M. 2012. “The Challenges of Bankruptcy Reform.” World Bank Research Observer, World Bank Group, vol. 27(2): 185-203; Carcea M.C., Ciriaci D., Cuerpo Caballero C., Lorenzani D., and Pontuch P. 2015. “The Economic Impact of Rescue and Recovery Frameworks.” European Commission Discussion Papers; El Ghoul S., Fu Z., Guedhami O. 2021. “Zombie firms: Prevalence, determinants, and corporate policies.” Finance Research Letters 411. A study of 19 years of bankruptcy data in 29 countries shows that entrepreneur-friendly bankruptcy laws are significantly correlated with the level of entrepreneurship development as measured by the rate of new firm entry (Lee S., Yasuhiro Y., Peng M. W., and Barney J. B 2011. “How do bankruptcy laws affect entrepreneurship development around the world?” Journal of Business Venturing 26(5): 505-520. 179 Polo A. 2011. “Preservation of Value, Conflict of Interests and Reputation in a ‘Contractualist’ Bankruptcy System.” Paper delivered at reputation Symposium 2011 at Oxford University Centre for Corporate Reputation; McGowan M. A., Andrews D., and Millot V. 2018. “The walking dead? Zombie firms and productivity performance in OECD Countries.” Economic Policy 33: 685-736; Białkowski M. 2018. “International insolvency proceedings – desired directions of change and implementation.” Service Management Journal 6: 37-42; Neira J. 2019. “Bankruptcy and cross-country differences in productivity.” Journal of Economic Behavior & Organization, Elsevier, 157(C): 359-381; Hemingway B. 2020. “Macroeconomic implications of insolvency regimes.” Bank of Lithuania Working Paper Series. 180 Andrew D. and Petroulakis F. 2017. “Breaking the shackles: Zombie firms, weak banks and depressed restructuring in Europe.” ECB Working Paper, No. 2240; Banerjee R., and Hofmann B. 2018. “The rise of zombie firms: causes and consequences.” BIS Quarterly Review 2: 67-78; McGowan M. A., Andrews D., and Millot V. 2018. “The walking dead? Zombie firms and productivity performance in OECD Countries.” Economic Policy 33: 685-736; Blattner L., Farinha L., and Rebelo F. 2019. “When losses turn into loans: The cost of undercapitalized banks.” ECB Working Paper No. 2228; Acharya V.V, Eisert T., Eufinger C., and Hirsch C. 2019. “Whatever it takes: the real effects of unconventional monetary policy.” The Review of Financial Studies 21(9): 3366-3411. 181 A recent study on Italy shows that an increase in recovery rate and a reduction in the length of proceedings would increase average productivity by about 2% (González-Torres G., and Rodano G. 2020). “Court Efficiency and Aggregate Productivity: The Credit Channel.” Bank of Italy Temi di Discussione (Working Paper) No. 1287. 53 the scope compared to the Doing Business Resolving Insolvency indicator. They will include new aspects of pre-insolvency proceedings, specialized proceedings for micro and small enterprises, insolvency administrator’s expertise, and measures of institutional infrastructure for insolvency processes. The indicators will focus on liquidation and reorganization proceedings (insolvency) only, with no specific case study scenario. They will also address environmental obligations in bankruptcy and review good environment regulatory practices within insolvency proceedings. 2. Indicators in the area of Business Insolvency BEE uses three sets of indicators in the area of business insolvency: (a) the quality of regulations for insolvency proceedings (regulatory pillar), (b) the quality of institutional and operational infrastructure for insolvency processes (public services pillar), and (c) the ease to resolve an insolvency judicial proceeding (which reflects a combination of the previous two pillars). a. Quality of regulations for insolvency proceedings The first set of indicators will measure the quality of insolvency regulations applicable to judicial liquidation and reorganization procedures in each economy, and how they compare to internationally recognized good practices. The proposed indicator will benchmark the quality of insolvency regulations through specific proxies that are closely linked with the objectives and adequately capture the good practices set out in the World Bank Principles for Effective Insolvency and Creditor/Debtor regimes and the United Nations Commission on International Trade Law (UNCITRAL) Legislative Guide on Insolvency Law. International good practices suggest that the law should clearly establish that debtors and creditors can apply for insolvency proceedings and include a formal process for submitting the application with a defined commencement criterion.182 Good practices also entail the implementation of efficient and transparent regulatory mechanisms for managing the debtor’s assets during the proceedings, as this may improve the likelihood of a high recovery.183 The chance of a mutually beneficial outcome is also increased if creditors’ rights are adequately protected, as their participation in the insolvency process balances the actions of the debtor and/or insolvency administrator.184 Finally, good practices advocate for promoting specialized or simplified proceedings for micro and small enterprises (MSMEs).185 In many cases, by the time the MSME debtor initiates insolvency proceedings, the firm is no longer viable, which results in a loss of value, compromising the preservation of the company at the expense of legal procedural certainty.186 This set of indicators falls under the regulatory pillar as it relates only to de jure elements based on the reading of the law. The indicator will also reflect burdensome regulations and normative gaps when good practices are not implemented. The data will be collected through expert consultations with local insolvency lawyers and data verification through desk research and a study of the applicable laws. No case study will be used. The quality of regulations for insolvency proceedings will have six indicators. (1) Commencement of insolvency proceedings – The indicator will include questions such as whether the debtor and the creditors can file for liquidation and/or reorganization proceedings, and the rules governing the stay of proceedings. It will also measure, for instance, which proceedings are available 182 World Bank Principles for Effective Insolvency and Creditor/Debtor regimes the United Nations Commission on International Trade Law (UNCITRAL) Legislative Guide on Insolvency Law. 183 Op. cit.World Bank and the United Nations Commission on International Trade Law. 184 Op. cit.World Bank and the United Nations Commission on International Trade Law. 185 Guerra-Martinez A. 2021. “Implementing an insolvency framework for micro and small firms.” International Insolvency Review 30(S1): S46-S66. 186 IMF Global Financial Stability Report: Moving from Liquidity to Growth Driven Markets 2014 54 for companies in financial distress predating the actual filing for insolvency. The indicator will therefore assess the legal avenues available to treat the imminent insolvency of corporate debtors, including availability of early warning tools and the extent of directors’ duties to file for insolvency. (2) Management of debtor’s assets – The indicator will measure what happens with the contracts, transactions, and finance of the debtor company during insolvency proceedings. The questions will include, for instance, whether the debtor can continue transactions essential to the survival of the business or terminate contracts that are overly burdensome. It will also test whether the law establishes that preferential and undervalued transactions made by the debtor prior to the commencement of insolvency can be avoided. This indicator will also measure the debtor’s ability to discharge environmental liabilities, including asset retirement obligations. (3) Scope of liquidation and reorganization proceedings – The indicator will measure key features of modern liquidation and reorganization proceedings. It will include questions on how the reorganization plan is approved, equity considerations for its approval, mechanisms for implementation, and protections available to dissenting creditors. It will also measure how the company’s management is replaced by an insolvency representative and the creditors’ role in approving the sale of assets in liquidation proceedings. This indicator will also measure whether the reorganization plan and liquidation proceedings must address environmental issues and ensure compliance with environmental law. (4) Creditor participation – The indicator will measure how creditors participate in important decisions during insolvency proceedings, with specific questions measuring, for instance, whether creditors participate in the appointment of the insolvency representative, whether creditors can object to decisions affecting their rights and the rules governing the priorities of creditors within insolvency proceedings, including any possible priorities of environmental claims. (5) Insolvency administrator’s expertise – The indicator will measure whether the professional insolvency practitioner framework is comprehensive, including features such as qualification, training, monitoring, and licensing or registration requirements. (6) Specialized proceedings for MSMEs – The indicator will measure whether aspects related to liquidation and reorganization procedures tailored for MSMEs are available under the insolvency regulation. It will include a general question on the availability of such specialized proceedings and specific questions measuring the type of features available, such as the existence of debt discharge safeguards for good faith individual debtors, shorter statutory limits, intensity of court supervision, simplified and fast-track proceedings. b. Quality of institutional and operational infrastructure for insolvency processes This set of indicators will measure the quality of insolvency resolution mechanisms and infrastructure required to successfully implement the legal framework on insolvency. This set of indicators seeks to reflect the de facto situation and focuses on relevant proxies measuring the functioning of institutions providing public services. For instance, the features measured promote faster resolution, reliable decision-making, transparency, and predictability, thereby serving as suitable proxies for the efficiency and quality of the insolvency regime. The data will be collected for the relevant court through expert consultations with users (including judges, clerks, auctioneers, insolvency representatives/trustees, official receivers and local insolvency practitioners). Desk research and administrative data collected by courts can be used to corroborate the data collected. The quality of insolvency resolution mechanisms and infrastructure for insolvency processes will have three indicators: 55 (1) Specialization of bankruptcy courts or bankruptcy judges – The indicator will measure whether a specialized bankruptcy court, a judge/division in a commercial court dedicated to bankruptcy matters exists and is fully operational (requiring all bankruptcy matters to be assigned to them), or whether bankruptcy matters are assigned to existing commercial courts; Specialized courts positively impact bank funding decisions,187 lead to faster resolution and reliable decision-making.188 It will also measure if specialized training on insolvency procedures is provided on a systematic basis to judges adjudicating bankruptcy matters. (2) Court automation and public availability of information – The indicator will measure if bankruptcy cases, and associated pleadings can be filed electronically through a dedicated platform; if court fees can be paid electronically; and if an online docketing system case is available. It will also measure whether an online docketing system can be accessed by the public and whether judgments and decisions on bankruptcy matters are made publicly available. Public availability of information enhances transparency and predictability,189 thereby serving as suitable proxies to measure efficiency and quality of the insolvency regime. (3) Interoperability of services for insolvency proceedings – The indicator will measure the implementation of an integrated database that gathers information of the debtor, the creditors, various collateral registries, and relevant agencies with a role in the insolvency proceedings. c. Ease to resolve an insolvency judicial proceeding This set of indicators will measure the time and cost to resolve an in-court liquidation and reorganization proceeding. The likely time to resolve the proceeding will be presented in calendar months from the filing until the payment of some or all of the money owed to creditors or approval of the reorganization plan. The overall cost of the proceeding (costs incurred by both the creditors and the borrower) will be recorded as a percentage of the value of the defined company’s debt. The data will be collected based on assumptions underlining the defined company, including its type and size, as well as the value of claim. This set of indicators will not require a case study. The data will be gathered through expert consultations with local insolvency experts and verified through desk research. This measure of efficiency serves as a suitable proxy for the efficiency of the judicial proceedings on insolvency. Cost-effective and time efficient insolvency proceedings can encourage inefficient firms to exit, embolden greater entrepreneurial activity and new firm creation.190 The objective of this set of indicators is to reflect the red tape involved in resolving insolvency disputes. 187 Rodano G., Serrano-Velarde N., and Tarantino E. 2016. “Bankruptcy law and bank financing.” Journal of Financial Economics 120(2): 363–382. 188 Li B., and Ponticelli J. 2020. “Going Bankrupt in China.” National Bureau of Economic Research Working Paper Series, 4; Iverson B. C., Madsen J., Wang W., Xu Q. 2018. “Learning by doing: Judge experience and bankruptcy outcomes.” (Available at https://www.aeaweb.org/conference/2019/preliminary/paper/QizYKHeB ) 189 Byfield, Paul. 2011. “The Publication of Commercial Court Decisions in the Western Commonwealth of Independent States.” 190 Kruczalak-Jankowska J., Maśnicka M., and Machnikowska A. 2020. “The relation between duration of insolvency proceedings and their efficiency (with a particular emphasis on Polish experiences).” International Insolvency Review, 29(3): 379- 392. 56 Section III. Features of Implementation A. Data collection approach The BEE project uses two main data collection approaches: expert consultations and firm-level surveys. Expert consultations refer to data collection from experts who regularly deal with the relevant legal arrangements, public services, and institutions providing those services. Firm-level surveys refer to data collection from a representative sample of actual, formal firms. Moreover, the team can use two corroborating mechanisms for the data collected through expert consultations on regulations and public services: desk research (i.e., the reading of laws/regulations, checking of features on public websites) and official data (i.e., administrative statistics from registries, courts, and other agencies). 1. Suitability for different indicators: Expert consultations are suitable for indicators measuring the quality of regulations, the existence of features or good practices in public services, and the implementation of regulations and public services for “rare events,” that is, those that do not occur widely or regularly in the firms’ lifecycle. Firm-level surveys are suitable for indicators measuring the de facto implementation of regulations and public services during the operational stages of businesses, including the uptake and engagement with specific practices. Generally, firm-level surveys will be an inefficient way to gather information on rare events (e.g., company registration, insolvency) or where no variation across firms is expected (e.g., official fees that apply equally to different types of firms). 2. Comparability: Expert consultations ask experts questions about groups of firms of similar characteristics and allow for the comparison of the experience of such firms across economies. In some cases, standardized case studies can provide a further degree of comparability. Firm-level surveys ask respondents questions about their own firms and allow for the comparison of the typical experience (a representative mean, median, or other similar statistic) of actual firms, with the added benefit of providing information on variability across firms. 3. Representativeness/relevance: Expert consultations provide less representativeness than firm-level surveys if specific assumptions about the firms are needed to administer the questions. Still, this approach can capture some variation by asking experts about different categories of firms (e.g., by legal form, size, and sector). Firm-level surveys provide more representativeness—and hence relevance to the economy— than expert consultations. The approach allows capturing the variation in firm-level experiences by their precise characteristics, including ownership, age, size, and sector. 4. Implementation: Expert consultations can be significantly less onerous and costly than firm-level surveys. To preserve the anonymity of contributors, secure their participation, and promote their accountability, a fee-based approach may need to be considered for experts to contribute. Firm-level surveys are more labor intensive and can be comparatively expensive, prohibitively so for only one or two pieces of information. For expert consultations, local experts can be identified through desk research, peer referrals, and DECIG’s online Contributor Engagement and Expert Nomination Portal. Screening questions will be used to sort out qualified respondents, based on their regular contact with the local and national regulatory and administrative systems, and their recent experiences undertaking the public services under study. Remunerating respondents can help preserve their anonymity and ensure the quality of responses. 191 191 Two alternative approaches were considered: obtaining/building a sampling frame of experts (that is representative of all relevant experts) or creating a broad pool of experts (that does not aim to be representative) and draw randomly from either of them. While these alternative approaches can help reduce the risk of undue influence and status quo bias, it is probably not feasible to obtain/build such a sampling frame or create a broad pool of potential respondents in every economy, or it will be prohibitively expensive to do so. 57 Moreover, blank questionnaires (instead of pre-filled questionnaires with information from the previous year) will be sent to experts in both the first and subsequent years. This approach can help remove the potential risk of anchoring bias, although it may lead to more year-to-year changes and volatility in the data compared to Doing Business. There are different types of firm-level surveys with different samples. For some indicators, the WBG’s Enterprise Surveys already have relevant modules or can include additional questions (e.g., cost of compliance with regulations to obtain utility connections, ease of access to finance). For some indicators, modules can be developed and administered as part of a follow-up survey to the main Enterprise Survey (e.g., labor practices, sustainable business practices). In economies where Enterprise Surveys do not exist or are outdated (e.g., for Brazil the latest Enterprise Survey was conducted in 2009), baseline information about firms needs to be collected to allow for follow-up surveys. Conducting ad hoc surveys, which target firms with specific types of experiences, is not recommended because the sample of firms eligible for such ad hoc surveys will be difficult to obtain and the absence of economies of scale across indicators would make the exercise even more expensive. B. Assessment of Skills This section looks at the required size, professional training, and seasonality for the various indicators within the BEE project. The assessment takes into consideration each indicator’s scope, data collection needs, and methodology used. For instance, indicators that heavily involve the analysis of the regulatory framework – including laws, jurisprudence, and understanding of court functions – will require team members with a legal background (e.g., Dispute resolution, under the quality of regulations for commercial dispute resolution set of indicators, assesses good regulatory practices of in-court commercial litigation processes). Whereas indicators that heavily involve expert consultations on procedural aspects will need members with training in economics and strong data management skills (e.g., Utility connections, under the utility performance and transparency of utility services set of indicators, assesses de facto measures on the provision of utility services such as frequency of outages). Indicators where data is collected through firm-level surveys (e.g., International trade, under the efficiency of importing goods, exporting goods, and engaging in e-commerce set of indicators, assesses the time and cost to trade as experienced businesses on the ground) will benefit from members with strong statistical skills and experience working with micro data and software (such as R or Stata). All indicators will require a combination of skills; that is, the teams would ideally include a combination of professionals trained in law, economics, statistics, and public policy. Every team will ideally require at least one person trained in economics and/or statistics to conduct analytical work, which will be particularly relevant for indicators collecting data through firm-level surveys. Professionals with a legal background will also play a key role since most indicators require the analysis of laws and regulations. Certain indicators will require members with specialized technical knowledge (e.g., Taxation will ideally require some team members trained in tax accounting). Team members trained in public policy would be desirable for indicators that assess broader policy areas such as Market competition. In addition to these professional backgrounds, every indicator will require at least one topic leader with project management skills to organize each teams’ work. C. Frequency and coverage of data collection and reporting Although annual frequency of the full set of indicators is desirable, given resource constraints it may be more realistic to consider a staggered report, where a fraction of the dataset is renewed every year. 58 D. Preliminary Timeline The target date for Bank-Wide Review is late-March 2022. The target date for Bank-Wide Review Meeting on the BEE Concept Note is mid-April 2022. The target timeline for releasing the first report is late fall 2023. See Table 2 for a preliminary timeline. Table 2. Preliminary Timeline for the BEE Project BEE Pre-Concept Note December 14, 2021 BEE objectives and principles discussion with Council of Chief Economist January 11, 2022 Briefing at the MVP + IFC meeting January 18, 2022 Briefing to the Board of Executive Directors End January 2022 Complete Pre-Concept Note, considering internal expert feedback February 8-March 8, 2022 Open consultations BEE Concept Note April 21, 2022 TBC Bank-Wide Review Meeting on the BEE Concept Note May 31, 2022 Concept Note discussion with the Board BEE Piloting June 15, 2022 BEE pilot questionnaires/surveys begin October 20, 2022 Data collected for all pilot economies December 15, 2022 BEE pilot data coded and shared on the website First BEE Data and Report January 2023 Data collection for the first edition of the BEE report Last trimester of 2023 First edition of the BEE report 59 Appendix I. Comparison of DB and BEE Key Features Doing Business Business Enabling Environment Benchmark assessment of the business Benchmark assessment of business Overview environment affecting individual small regulations and public services affecting and medium-size enterprises (SMEs). private sector development as a whole. Balanced focus on both the regulatory Focused on business regulations, with Scope framework and the provision of public some consideration of public services. services key for functioning markets. Balanced coverage of de jure and de facto Some indicators only covered de jure aspects of the regulatory framework and regulations, while others only looked at Data public services. De facto data collected de facto. Data collected through expert collection through a combination of expert consultations. Extended use of case consultations and firm-level surveys. studies to enhance comparability of data. Selective use of case studies.* DB topics were in principle selected to follow the life cycle of the firm but were BEE topics are also selected to follow the uneven regarding their relative life cycle of the firm, including its Topics importance. For example, including participation in the market. All topics are, “protecting minority investors” does not in principle, equally as important; and no appear well-justified; while excluding major omission will be allowed. “employing labor” is a clear omission. Indicators grouped under (1) efficiency All topics will be consistently structured of business regulations and (2) quality of under three sets of indicators: (1) business regulations. However, not all regulatory framework, (2) public services, Indicators topics were consistently structured under and (3) efficiency indicators. Moreover, these groupings. Moreover, indicators without the restrictions of narrow case were driven by the assumptions of the studies, the indicators can reveal case-study approach, limiting their information that better represents the representativeness. economy. Economies’ performance will be assessed Economies’ performance assessed based based on quantifiable indicators. on rankings and scores. Strong focus on Whether/how indicators will be grouped to Scoring aggregate rankings to maximize public produce aggregate scores is yet to be interest and motivate reforms. decided. Hype around rankings will be avoided. Main business city in 191 economies. Preferably as wide as possible regarding Second largest business city also country and within-country coverage. Coverage measured in 11 economies. Within-country coverage may differ across topics depending whether applicable regulations are national or local.* Annual for indicators based on expert consultations and staggered (e.g., in a 3- Update Annual. year cycle) for indicators obtained from firm-level surveys.* * BEE precise coverage, update, and data collection modality will depend on quality/cost considerations. 60 Appendix II. Detailed Preliminary BEE Topics and Indicators Data collection Pillar approach Stage Set of indicators Regulat Public Components De jure Expert Firm- Case ions services or de consulta level study facto tions surveys Opening Business entry a business Quality of regulations ✓ Good practices in the regulatory De jure ✓ for business entry framework for business incorporation;▵ Restrictions in the regulatory framework for business entry▵ Digital public services ✓ Availability of online services for De facto ✓ and transparency of business incorporation and information for beginning of operations;*▵ business start-ups Interoperability of services for business incorporation and beginning of operations;* Availability of company information online and transparency of information* Efficiency of business ✓ ✓ Time to incorporate and start De facto ✓ ✓ entry operating a new firm; Cost to incorporate and start operating a new firm Business location Quality of regulations ✓ Good regulatory practices for land De jure ✓ for immovable property administration; lease, property Good regulatory practices for ownership and urban building regulations;▵ planning Restrictions on property leasing and ownership 61 Data collection Pillar approach Stage Set of indicators Regulat Public Components De jure Expert Firm- Case ions services or de consulta level study facto tions surveys Quality of public ✓ Availability of online services and De facto ✓ services and reliability of infrastructure for transparency of property transactions;* information Interoperability of services for property transactions; Availability of online information on immovable property;* Availability of online services for building permitting and environmental licensing;*▵ Interoperability of building permitting systems; Transparency of information for building and environmental licenses*▵ Efficiency of key ✓ ✓ Time and cost to purchase a De facto ✓ services in getting a property; business location Time and cost to obtain building- related permits; Time and cost to obtain environment-related permits▵ Operating Utility connections a business Quality of utility ✓ Regulatory framework for De jure ✓ regulations electricity, water, and internet connections;*▵ Safety of utility connections* Utility performance ✓ Monitoring of key performance De facto ✓ and transparency of indicators on the quality, utility services reliability, and sustainability of utility supply;*▵ 62 Data collection Pillar approach Stage Set of indicators Regulat Public Components De jure Expert Firm- Case ions services or de consulta level study facto tions surveys Transparency of tariffs and connection requirements;* Interoperability of utility services* Efficiency of ✓ ✓ Time to obtain electricity, water, De facto ✓ implementation of and internet connection; utility regulations and Cost to obtain electricity, water, services and internet connection; Reliability of electricity, water, and internet services Labor Quality of labor ✓ Workers' protection; De jure ✓ ✓ regulations Employment restrictions Adequacy of public ✓ ✓ Workers' social protection; De facto ✓ services for the labor Public employment services;* market Individual labor disputes* Ease of employing ✓ ✓ Workers' protection; De facto ✓ labor Employment restrictions; Workers' social protection; Public employment services;* Individual labor disputes* Financial services Quality of regulations ✓ Quality of regulations for secured De jure ✓ for secured transactions, including integrated transactions, e- legal framework for secured payments, and green transactions and enforcement of financing security interests in movable assets 63 Data collection Pillar approach Stage Set of indicators Regulat Public Components De jure Expert Firm- Case ions services or de consulta level study facto tions surveys Quality of regulations for e- payments, including robust risk management, protection of customer funds, transparency of fees, terms, and conditions, availability of solid recourse and dispute resolution mechanism, accessibility and integrity, and promotion of competition* Quality of regulations for green financing, including sustainable finance regulation, green bonds issuance, significance of green bonds, and transparency requirements▵ Quality of credit ✓ Operationalization of credit De facto ✓ reporting framework bureaus and registries;* Operationalization of collateral registries* Ease of receiving ✓ ✓ Ease of making an e-payment, De facto ✓ financial services including time and cost to make an e-payment through internet banking, mobile banking, e- money, and payment cards for B2B and P2B;* Time to obtain a loan International trade Quality of regulations ✓ Good regulatory practices enabling De jure ✓ for international trade international trade; 64 Data collection Pillar approach Stage Set of indicators Regulat Public Components De jure Expert Firm- Case ions services or de consulta level study facto tions surveys in goods and e- Good regulatory practices enabling commerce e-commerce;* Good regulatory practices enabling environmentally sustainable trade;▵ Regulatory restrictions on international trade; Regulatory restrictions on e- commerce* Quality of public ✓ Transparency and availability of De facto ✓ services for the information;* promotion of Electronic systems and international trade in interoperability of services;* goods Risk management; Customs programs; External cooperation; Trade infrastructure Efficiency of importing ✓ ✓ Operationalization of risk De facto ✓ goods, exporting management system; goods, and engaging in Implementation of border agency e-commerce programs; Time and cost to comply with export requirements; Time and cost to comply with import requirements; Time and cost to engage in e- commerce* Taxation 65 Data collection Pillar approach Stage Set of indicators Regulat Public Components De jure Expert Firm- Case ions services or de consulta level study facto tions surveys Quality of tax ✓ Addressing clarity of tax De facto ✓ regulations provisions;▵ Stability of tax regulations;▵ Complexity of record keeping and filing; Transparency in the formulation of tax regulations▵ Services provided by ✓ Electronic systems for tax filing, De facto ✓ the tax administration payment, and assessment;* Risk-based audit; Dispute resolution mechanisms; Transparency of tax administration Tax burden and ✓ ✓ Total tax and contribution rate; De jure ✓ ✓ ✓ efficiency of tax Time to comply with tax De facto ✓ systems regulations*▵ Dispute resolution Quality of regulations ✓ Quality of regulations applicable De jure ✓ for commercial dispute to in-court litigation processes; resolution Quality of regulations governing alternative dispute resolution mechanisms (arbitration and mediation) Adequacy of public ✓ Institutional framework; De facto ✓ services in commercial Court automation and e-services* litigation Ease of resolving a ✓ ✓ Obstacles to justice; De facto ✓ commercial dispute Time to resolve a commercial ✓ dispute; Cost of a commercial dispute ✓ 66 Data collection Pillar approach Stage Set of indicators Regulat Public Components De jure Expert Firm- Case ions services or de consulta level study facto tions surveys Market competition Quality of regulations ✓ Quality of competition regulations; De jure ✓ that promote market Quality of regulations for bidding competition for public contracts▵ Adequacy of public ✓ Institutional framework and De facto ✓ services that promote quality of enforcement of market competition competition regulations;* Transparency and transactional features in electronic procurement platforms*▵ Efficiency in the ✓ ✓ Effective implementation of the De facto ✓ implementation of key simplified merger review; services promoting Time to award a public contract; ✓ market competition Time to pay government ✓ contractors; Market dynamism and competitive ✓ behaviors Closing a Business insolvency business Quality of regulations ✓ Commencement of insolvency De jure ✓ for insolvency proceedings; proceedings Management of debtor's assets; Scope of liquidation and reorganization proceedings;▵ Creditor participation;▵ Insolvency administrator's expertise; Specialized proceedings for MSMEs 67 Data collection Pillar approach Stage Set of indicators Regulat Public Components De jure Expert Firm- Case ions services or de consulta level study facto tions surveys Quality of institutional ✓ Specialization of bankruptcy De facto ✓ and operational courts or bankruptcy judges; infrastructure for Court automation and public insolvency processes availability of information;* Interoperability of services for insolvency proceedings* Ease to resolve an ✓ ✓ Time to resolve an in-court De facto ✓ insolvency judicial liquidation or reorganization proceeding proceeding; Cost of an in-court liquidation or reorganization proceeding Note: Together with the preliminary topics listed above, BEE will look at two cross-cutting themes relevant across topics: the adoption of digital technologies and environmental sustainability. The * symbol denotes components that will cover the adoption of digital technologies. The ▵ symbol denotes components that will cover environmental sustainability. 68
 海关法规查询系统